
Market Intelligence | North Carolina

Charlotte

NC Multifamily Investment Market Report

Charlotte is absorbing one of the two or three largest multifamily construction pipelines in the country— and doing it with tighter vacancy, faster job growth, and a deeper banking-sector anchor than almost any other market in this series.

August 2026

Mid-2026 Outlook

On this page

Executive summary

Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.

Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.

Charlotte, North Carolina serves as our eleventh edition and the first North Carolina market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Charlotte exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.

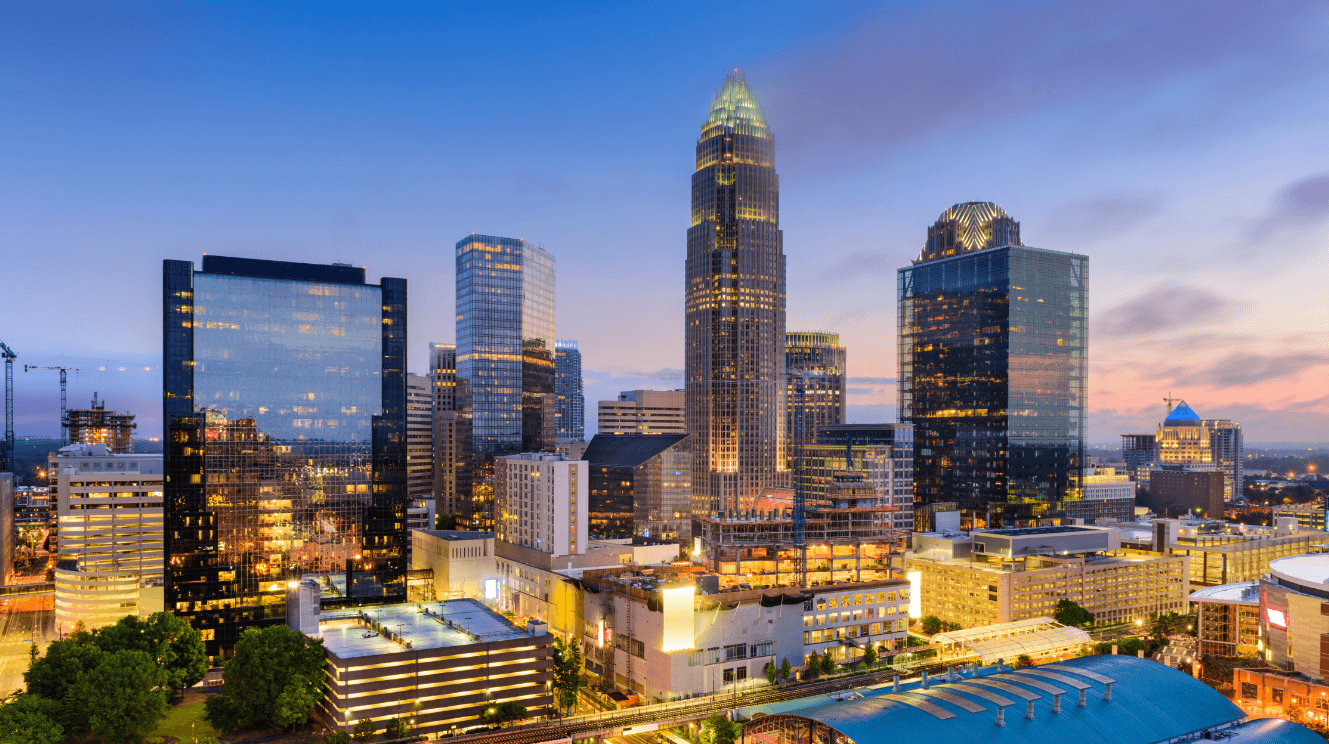
This Is What Charlotte Looks Like

Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report delivers an independent, data-driven assessment of the Charlotte multifamily sector as of mid2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
~$1,516–1,578
Average Rent per Unit
−0.3% to −3.2%
Rent Growth: 11 Consecutive Quarters of YoY Decline
~6.2–8.4%
Overall Vacancy
~$1.6–2.3B (trailing 12mo)
Multifamily Deal Activity
~18,000–27,000 units
Units Under Construction
Sources: Yardi Matrix, CoStar Group, Marcus & Millichap, Northmarq. Data as of Q1–Q2 2026.
Absorbing One of the Nation's Largest Pipelines — Comparatively Well

Charlotte’s active multifamily construction pipeline ranks among the two or three largest in the country, trailing only Miami (also covered in this series) and running roughly even with Nashville. Vacancy estimates range from approximately 6.2% (CoStar-style, Q1 2026) to 8.2–8.4% (Northmarq, trending toward the mid-8% range in 2026), with rents down on a trailing year-over-year basis for 11 consecutive quarters.


What distinguishes Charlotte from several other high-supply metros in this series is the strength of the demand absorbing that pipeline: the metro added approximately 33,900 net jobs over the trailing 12 months (Yardi Matrix), professional and business services alone contributed 9,000 positions, and annual absorption has approached record levels in back-to-back years. Cap rates, at approximately 5.0%, sit below both the South region average (5.39%) and the national average (5.41%).

Current indicators point to supply peaking against an unusually strong demand base:
  • Construction starts fell nearly 40% year-over-year in 2024, signaling materially fewer deliveries ahead in 2026 and beyond.
  • Annual absorption reached record or near-record levels in both 2024 and 2025, with 2025 net move-ins outpacing 2024’s peak by roughly 15% in one reading.
  • Matthews projects Charlotte rents to return to positive growth in 2027, forecasting +1.8% over the next 12 months as supply and demand approach equilibrium.
  • Charlotte-Mecklenburg Police reported an 8% decline in overall crime and a 25% decline in violent crime in the first half of 2026 versus the same period in 2024.

Within the Longview portfolio, Charlotte reads as structurally closer to Atlanta than to the Texas or Florida markets in this series: a large, high-quality metro absorbing significant new supply on the strength of a genuinely diversified, high-wage employment base rather than purely migration-driven growth.
General Metro Charlotte Metrics

Economy & Demographics

Population figures vary by geographic definition. The Charlotte MSA reached approximately 2.27–2.32 million as of recent estimates, while the broader 18-county combined statistical area (CSA) reached approximately 3.47 million as of 2024. The City of Charlotte itself is estimated at approximately 920,000–1.03 million depending on source. Charlotte was ranked the #2 U-Haul Growth City in 2024, and added more housing units than new households in 2024 — rare supply-side relief in a still-booming metro.

Employment & Labor Force
Charlotte added approximately 33,900 net jobs in the 12 months ending August 2025 (Yardi Matrix), with professional and business services leading at 9,000 positions. Unemployment stood at 3.8% as of September 2025, only 10 basis points above the North Carolina average. Northmarq characterized Charlotte’s labor market as among the strongest in the country.
Job Diversity & Industry

Charlotte is the second-largest banking center in the U.S. after New York, anchored by Bank of America (headquartered downtown, one of the nation’s largest banks by total assets) and Truist Financial ($500+ billion in assets). Wells Fargo maintains its East Coast headquarters here, and the metro supports 100,000+ financial services jobs. Beyond banking, Charlotte hosts Honeywell’s HQ, Lowe’s Global Technology Center, and a growing fintech ecosystem (nCino, LendingTree) alongside recent expansions from SMBC, Citigroup, and TD Bank.

Fortune 500 Headquarters

Charlotte’s metro is home to seven to nine Fortune 500 companies depending on the year, including Bank of America, Truist Financial, Honeywell, Nucor, Lowe’s, Duke Energy, Sonic Automotive, and Brighthouse Financial — among the deepest Fortune 500 concentrations of any market in this series, reflecting genuine national financial hub status rather than a purely regional business center.

Demographics & Renter Population
A young, well-educated renter base — median age approximately 34, with more than 40% of adults holding at least a bachelor’s degree. Housing costs run roughly 15% below the national average even amid rapid growth, and shorter-than-average commute times (~26.5 minutes) support quality-of-life appeal alongside the strong employment base.
Crime & Livability Trends

A genuinely strong, well-documented improvement. CMPD’s Mid-Year Public Safety Report found an 8% decline in overall crime and a 25% decline in violent crime in H1 2026 versus H1 2024, with homicides down 29%, aggravated assaults down 25%, and robberies down 21%. Property crime was more mixed, down 5% overall with slight increases in specific categories. Crime remains concentrated in the city center relative to well-below-average suburban rates.

Overall, Charlotte combines one of the deepest corporate and financial-services employment bases of any market in this series with a genuinely improving public-safety trend and continued strong in-migration — set against one of the largest active construction pipelines in the country.

Multifamily Metrics vs. National Benchmarks

Rent, Occupancy & Transaction Detail

Rent, Occupancy & Transaction Detail

2024 Deliveries (Record Year)

~16,700 units

2025 Deliveries (Moderating)

~13,000-16,200 units

Charlotte’s combination of an outsized construction pipeline and an unusually strong, diversified employment base sets it apart from most other high-supply metros in this series. Where markets like Austin or San Antonio paired heavy supply with a more narrowly tech-or tourism-dependent demand base, Charlotte’s banking, financial-services, and corporate-headquarters economy has kept absorption running at or near record levels even through the peak of the supply cycle.

Current & Future Trends

CURRENT (2026)

Charlotte is absorbing one of the nation’s two or three largest active pipelines, with vacancy estimates ranging 6.2– 8.4% and rents down for 11 consecutive quarters.

Submarket performance diverges sharply: South End posted the strongest recent absorption despite a ~25% inventory expansion, while South Charlotte and University still carry rapidly growing pipelines (up 37% and 51% YoY).

Investment activity has shown early signs of recovery, with cap rates below both regional and national averages reflecting continued investor confidence.

5-YEAR OUTLOOK ( 2031)

With construction starts down nearly 40% in 2024, deliveries should moderate through 2026 and 2027, supporting a return to positive rent growth (Matthews projects +1.8% over the next 12 months).
Development has already tapered in North, West, and East Charlotte, positioning those areas for faster near-term recovery.

Equity remains selective, favoring value-add and preferred equity structures over new development given elevated urban construction costs (up to $300,000/unit in some submarkets).

10-YEAR OUTLOOK

Charlotte’s deep banking and financial-services base, combined with continued in-migration, should sustain one of the strongest demand profiles in this series.
Undersupplied outlying submarkets (Gaston County, Lake Norman) with occupancy above 94% offer a genuinely different risk profile than the urban core.
Properties delivered 2020–2023 are increasingly changing hands, presenting a growing pool of opportunities through the remainder of the decade.

Market Projection — Five Years From Now (~2031)

Important Statistics Snapshot

Charlotte Multifamily Market

Under construction—among the 2–3 largest pipelines in the nation

~18,000–27,000
units

Construction starts, 2024 vs. 2023 — signaling materially lighter future deliveries

−40%

Vacancy (source range; see Data Note on methodology)
6.2–8.4%
Average asking rent (source range)
~$1,516–1,578
Average cap rate — below South region (5.39%) and national (5.41%) averages
~5.0%

Charlotte Economy Statistics

Population (MSA vs. broader combined statistical area definitions)
~2.3–2.9M metro
Unemployment Rate
~4.3%
Job Growth: Positive in recent benchmarks
~1.4%
Net job growth, trailing 12 months (Yardi Matrix)
+33,900 jobs
Violent crime decline, H1 2026 vs. H1 2024 (CMPD Mid-Year Public Safety Report)
−25%
Key Notes/Drivers: Banking/finance (major hub), logistics, healthcare, manufacturing, and professional services. Strong growth and in-migration.

Main Companies & Market Players

Local & Regional
Crescent Communities, headquartered in Charlotte, is a nationally recognized developer with more than 95 multifamily communities delivered since 1963 and a current $7.2 billion pipeline including 15,300 multifamily and build-to-rent units, spanning offices in nine major U.S. markets.
National Platforms
Crescent Communities’ NOVEL, RENDER, and HARMON brands are active across multiple Charlotte submarkets, including the 1,400-acre River District master planned community in West Charlotte, alongside other active developers such as Atlanta-based Third & Urban and locally focused New Forum.
Investors

Investment activity is showing early signs of recovery after a cautious 2024–2025, with equity remaining selective and favoring value-add and preferred equity structures. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s supply cycle or industry base.

Opportunities
Submarket Intelligence

Submarket

Profile & Theme

Longview View

Gaston County & Lake Norman (Mooresville/ Statesville)
Occupancy above 94% with minimal new pipeline, offering attractive development and acquisition opportunities with far less competition than the urban core.

Favorable

South End
Posted the metro’s strongest recent absorption (2,500+ units since Q3 2024) despite a roughly 25% inventory expansion over the past year — a genuine bifurcation of heavy supply and equally heavy demand.

Selective

North, West & East Charlotte

Development has already tapered meaningfully in these corridors, positioning them for faster near-term vacancy recovery as the metro-wide pipeline thins.

Selective

South Charlotte & University
Still carry rapidly growing construction pipelines, up 37% and 51% year-overyear respectively — the metro’s clearest near-term supply risk.

Cautious

Data Note

Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.

Risks

In a Nutshell

Charlotte in 2026 is absorbing one of the two or three largest active multifamily pipelines in the nation, doing so with a demand base — anchored by one of the country’s deepest banking clusters — strong enough to keep absorption near record levels through the peak of the cycle. Vacancy remains elevated by some measures and rents have been under pressure for nearly three years, but construction starts have fallen sharply, cap rates remain tight versus national averages, and crime trends are genuinely improving. Within a diversified allocation, Charlotte pairs closely with Atlanta as a large, economically diversified metro working through a supply cycle on the strength of exceptional demand.

Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.

Contact and Next Steps