Executive summary
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.Columbia, South Carolina serves as our twenty-first edition and the second South Carolina market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Columbia exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
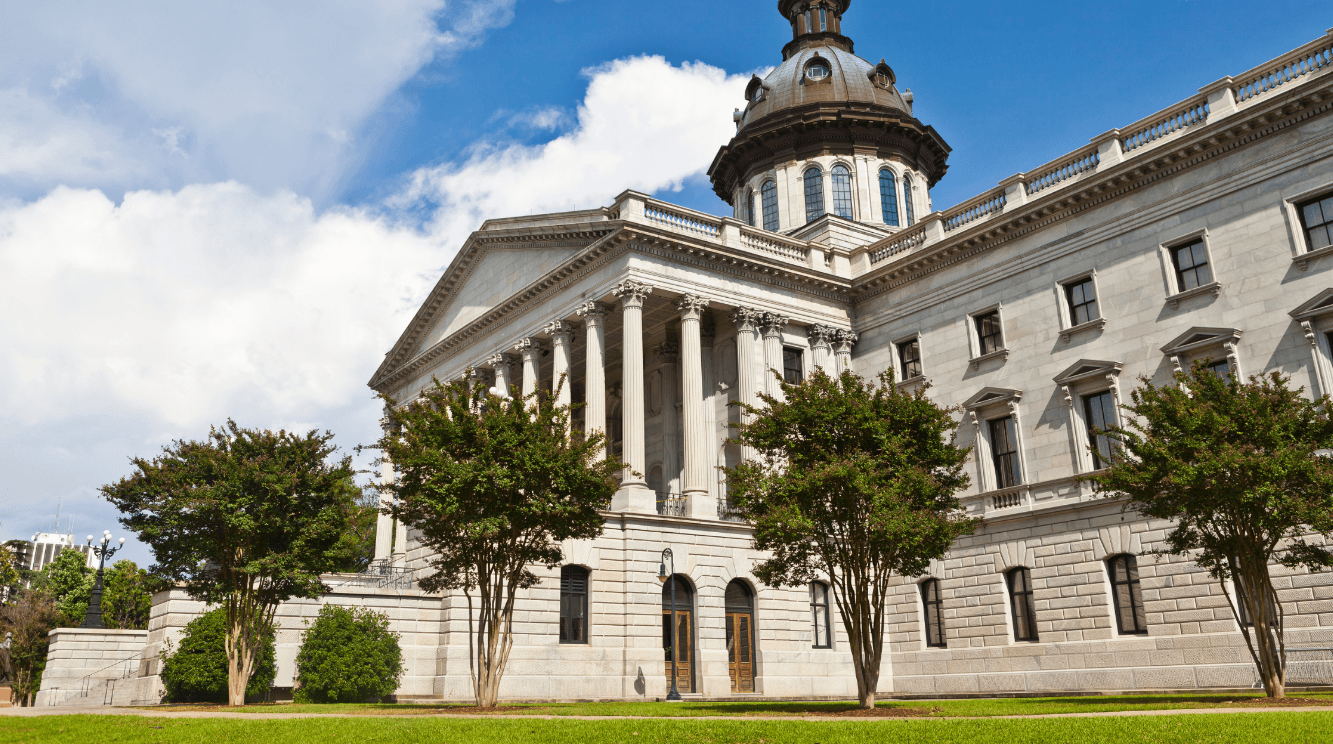
This Is What Columbia Looks Like
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report delivers an independent, data-driven assessment of the Columbia multifamily sector as of mid2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
~$1,350 (avg.) / ~$1,600 (downtown)
Average Rent per Unit
+1.8% YoY
Rent Growth: Positive, Steadier Than Larger SE Peers
Above historic average (metro) / 92.3% Class A Average Rent per Unit occ.
Overall Vacancy
Cap rates at 5.6%
Multifamily Deal Activity
~1,800 units (+25% downtown pipeline)
Units Under Construction
Sources: Colliers International, Columbia Metropolitan Magazine. Data as of Q1–Q2 2026.
A State Capital That Avoided the Worst of the Sunbelt Supply Wave
Columbia’s multifamily sector has experienced stable demand even as increased supply pushed vacancy above its historic average. Rents remain among the most affordable in the Southeast and are still showing positive gains at approximately 1.8% year-over-year — averaging $1,350 metro-wide and approximately $1,600 downtown. Class A occupancy, at 92.3%, exceeds historical averages even amid a 20-year construction peak.
Columbia has carried a comparatively modest construction pipeline relative to larger Southeast metros in this series: inventory has expanded roughly 7% since 2020, versus 8% growth in neighboring Greenville and Charlotte. Approximately 1,800 units remain under construction metro-wide, though the downtown-specific pipeline alone would add roughly 25% to the low-density urban core’s inventory once completed.
Current indicators point to a stable, if slower-growing, capital-city market:
- Class A occupancy of 92.3% exceeds historical averages despite a 20-year construction peak, according to Colliers’ most recent quarterly data.
- Workforce growth of 3.43% year-over-year (Colliers) is notably strong, though public-sector concentration keeps overall population growth (approximately 5% since 2020) behind neighboring Greenville and Charlotte (approximately 8%).
- Scout Motors’ Blythewood production facility, with capacity for 200,000 vehicles annually and more than 4,000 employees, is nearing completion and driving growth in the North Richland submarket specifically.
- Cap rates reportedly trade at a premium to comparable Atlanta and Charlotte product, reflecting the market’s relative supply discipline according to one regional research source.
Within the Longview portfolio, Columbia functions as a genuinely defensive Southeast holding: a public-sector- and universityanchored capital-city economy that has avoided the deepest oversupply cycles hitting several larger metros.
General Metro Charlotte Metrics
Economy & Demographics
Population figures vary by geographic definition. The six-county Columbia MSA reached approximately 777,000 to 856,889 depending on source, while the broader Columbia-Sumter Orangeburg combined statistical area reached approximately 1,082,699 as of 2023. The City of Columbia itself reached approximately 144,000–149,000. Metro-wide growth of approximately 5% since 2020 trails neighboring Greenville and Charlotte’s approximately 8%, attributed in part to Columbia’s outsized public-sector employment base.
Employment & Labor Force
The public sector employs roughly 20% of Columbia’s workforce — approximately 40% higher than the national average — providing a resilient economic base that insulates the metro from typical cyclical downturns, while also constraining growth relative to more private-sector-driven neighboring metros. Colliers cited workforce growth of 3.43% year-over-year, alongside a
separate employment growth estimate of 1.7%.
Job Diversity & Industry
Anchored by state government, the University of South Carolina (40,000+ students), and Fort Jackson, one of the U.S. Army’s largest Basic Combat Training installations. Manufacturing diversification is accelerating: Scout Motors is nearing completion of its
Blythewood facility, with capacity for 200,000 vehicles annually and 4,000+ planned employees. Recent commitments include a Right side Pharmaceuticals logistics operation and notable leases from Lularose, Winland Foods, and DSV.
Fortune 500 Headquarters
We did not identify a Fortune 500 company headquartered in Columbia. The metro’s economic weight instead comes from state government, the University of South Carolina, Fort Jackson, and accelerating manufacturing investment (Scout Motors) rather than corporate headquarters concentration.
Demographics & Renter Population
A renter base shaped significantly by the University of South Carolina’s 40,000+ students, concentrated near campus and competing directly with dedicated student housing from both private operators and the university itself. The broader pool also includes a substantial state-government and military-adjacent (Fort Jackson) workforce, contributing a more income-stable, if slower-growing, demand base.
Crime & Livability Trends
Genuinely conflicting depending on methodology. One tracker comparing Columbia to all U.S. communities of all sizes found its crime rate higher than 82% of South Carolina communities. Separate FBI-data-based analysis found reported burglary cases
increasing between 2022 and 2023, though we did not identify a clear, current, well-documented overall crime trend with the confidence available for some other markets in this series.
Overall, Columbia combines a defensive, public-sector- and university-anchored economy with a comparatively disciplined recent supply cycle — a genuinely different risk profile than the faster-growing, higher-amplitude Sunbelt metros that dominate much of this series.
Multifamily Metrics vs. National Benchmarks
Rent, Occupancy & Transaction Detail
Rent, Occupancy & Transaction Detail
Inventory Growth Since 2020 (Columbia)
Inventory Growth Since 2020 (Greenville/Charlotte)
Columbia’s defining characteristic in this series is relative stability rather than dramatic recovery or correction. Its public-sector heavy economy grows more slowly than neighboring Greenville and Charlotte, but that same structural feature appears to have kept the market from the deeper oversupply cycles affecting several larger Sunbelt metros in this series.
Current & Future Trends
Class A occupancy of 92.3% exceeds historical
averages despite a 20- year construction peak, and rent growth has remained positive at approximately 1.8% even as several larger Sunbelt peers posted declines.
The North Richland submarket has emerged as a key development hotspot, driven by rapid population growth and Scout Motors’ nearly complete Blythewood facility.
Cap rates reportedly trade at a premium to comparable Atlanta and Charlotte product, per one
regional research source we could not independently
corroborate.
With inventory growth of roughly 7% since 2020 —
below neighboring Greenville and Charlotte’s 8% —
Columbia’s more modest supply trajectory should
continue supporting relative stability through 2026.
The downtown construction pipeline alone would
add approximately 25% to the low-density urban
core’s inventory once completed, concentrating
near-term supply risk there specifically.
Investment activity in South Carolina secondary
markets has focused on stabilized acquisitions and
selective infill development in locations with strong
demographic profiles.
State government, the University of South Carolina,
and Fort Jackson provide a demand base with structurally lower cyclicality than more purely migration-dependent Sunbelt metros.
Properties near the University of South Carolina
compete directly with dedicated student housing, a
distinct competitive dynamic worth underwriting
separately.
Scout Motors’ 4,000+ planned jobs, still ramping
toward full capacity, represent a demand catalyst
substantially ahead of the market.
Market Projection — Five Years From Now (~2031)
Important Statistics Snapshot
Columbia Multifamily Market
Class A occupancy — exceeds historical averages despite a 20-year construction peak
92.3%
Average rent, metro-wide vs. downtown
~$1,350 / ~$1,600
Rent growth, year-over-year — positive even as larger Sunbelt peers declined
+1.8%
Average asking rent
$1,350
Projected 2026 rent growth (#2 nationally in
one forecast)
+4.1%
Cap rates, generally
5.6%
Columbia Economy Statistics
MSA population (source-dependent range); city proper ~144,000–149,000
~777,000–857,000
Metro population growth since 2020 — trails
Greenville/Charlotte’s ~8%
~5%
Share of work force in public sector — ~40% above the national average
20%
Unemployment Rate: Moderate (state SC ~4.8%; metro typically similar or slightly lower)
4.2%
Job Growth: Moderate/positive
1.7%
Jobs planned at Scout Motors’ nearly complete Blythewood EV plant (200,000 vehicle/yr capacity)
4,000+
Homicide rate remains higher than national medians
82% of SC communities
Key Notes/Drivers: Government/education (state capital), healthcare, manufacturing, and professional services. Steady regional hub.
Main Companies & Market Players
Local & Regional
We did not identify a single, dominant Columbia-headquartered multifamily developer comparable to the local anchors profiled in other editions of this series in our sourcing for this edition.
National Platforms
Colliers | South Carolina, the state’s largest full-service commercial real estate firm with approximately $1.5 billion in annual transaction volume, maintains an active Columbia presence alongside offices in Charleston, Greenville, and Spartanburg.
Investors
Investment activity in South Carolina secondary
markets has focused on stabilized acquisitions and selective ground-up development at infill locations with strong demographic profiles, with cap rates reportedly trading at a premium to comparable Atlanta and Charlotte product. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s growth rate or economic base.
Submarket Intelligence
Downtown Columbia
Higher-end rents (approximately $1,600) and 94.3% occupancy, though the concentrated construction pipeline here alone would add roughly 25% to urban-core inventory once completed.
North Richland (Blythewood)
Emerged as a key development hotspot driven by rapid population growth and
the nearly complete Scout Motors production facility.
University of South Carolina- Adjacent
Strong, durable student-driven demand, though properties here compete directly with dedicated student housing from both private developers and the university itself.
Data Note
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
In a Nutshell
Columbia in 2026 offers a genuinely different risk profile than the faster-growing, higher-amplitude Sunbelt metros that dominate much of this series: a state-capital economy anchored by government employment, the University of South Carolina, and Fort Jackson that has avoided the deepest oversupply cycles hitting several larger peers, evidenced by positive rent growth and above average Class A occupancy even amid a 20-year construction peak. Scout Motors’ nearly complete Blythewood EV plant adds a genuine new growth catalyst still largely ahead of the market. Within a diversified Southeast allocation, Columbia pairs with Greenville as a South Carolina complement to this series’ Atlanta and Charlotte exposure, trading faster growth for greater structural stability.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.nsult offering documents.