Executive summary
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
Knoxville, Tennessee serves as our twentieth edition and the third Tennessee market in this series in the Longview portfolio
strategy. As one of the nation’s most dynamic Sunbelt metros, Knoxville exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
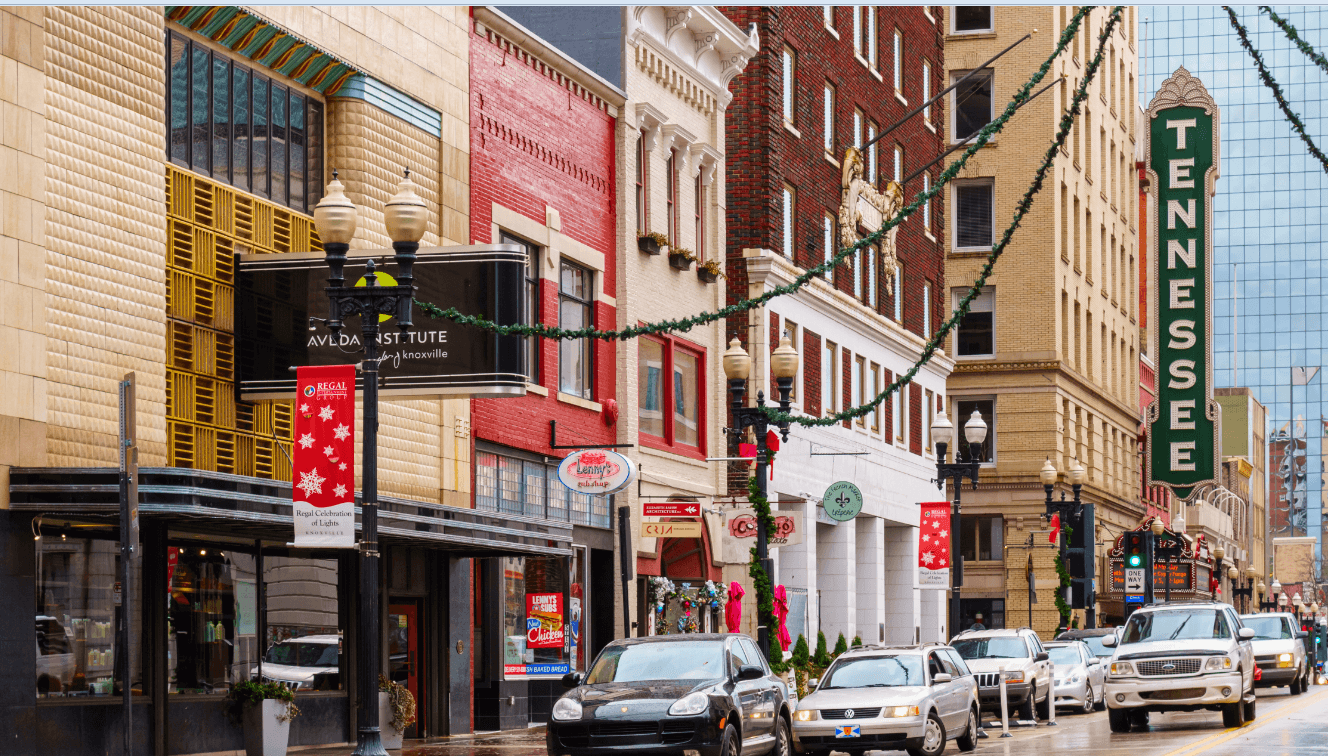
This Is What Knoxville Looks Like
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report delivers an independent, data-driven assessment of the Knoxville multifamily sector as of mid2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
~$1,430–1,470
Average Rent per Unit
−0.9% YoY / +1.9% (Q2 2026, QoQ)
Rent Growth: First Positive Quarter in a Year
~9% (allproperty) / ~93.3–94.9% occ. (stabilized)
Overall Vacancy
~$196M (2025)
Multifamily Deal Activity
−73% starts (Q2 2026)
Units Under Construction
Sources: Yardi Matrix, MMG Real Estate Advisors. Data as of Q1–Q2 2026.
A Softening Market Showing Its First Real Signs of Turning
Knoxville’s multifamily fundamentals softened through 2025 and into early 2026: advertised asking rents fell approximately 0.9% year-over-year to $1,470 in February, and stabilized occupancy declined 70 basis points to 94.9% — still above the 94.3% national average. Broader market occupancy, including recently delivered lease-up product, ran closer to 91%.
The most recent quarterly data point is meaningfully more encouraging: MMG Real Estate Advisors reported rents posting their first positive quarterly reading (+1.9%) in Q2 2026 after three consecutive quarterly declines, while absorption jumped to 592 units — nearly triple the prior quarter and the strongest quarterly showing in two years. Construction starts have collapsed approximately 73% to just 796 units, signaling supply should thin materially by late 2027.
Current indicators point to a market at, or very near, an inflection point:
- Construction starts fell approximately 73% to 796 units in the most recent reading, one of the sharpest pullbacks of any market in this series.
- Q2 2026 absorption of 592 units nearly tripled the prior quarter’s total and marked the strongest quarterly performance in two years.
- Rents posted their first positive quarterly reading (+1.9%) in a year, even though trailing annual growth remains negative.
- Employment grew 1.2% in 2025, double the 0.6% national rate, with unemployment at 2.9–3.2%, well below both Tennessee and U.S. averages.
Within the Longview portfolio, Knoxville reads as an earlier-stage version of the inflection already visible in Tampa and Orlando: a market where the most recent quarter’s data looks meaningfully better than the trailing-year trend, though one strong quarter is not yet a confirmed trend of its own.
General Metro Knoxville Metrics
Economy & Demographics
Population figures show some variance by source and geographic definition. The official nine-county Knoxville MSA reached approximately 903,300 at the 2020 Census, while a separate tracking series using what appears to be a narrower or differently weighted county definition cited approximately 807,000 for 2025. The broader Knoxville-Morristown-Newport-Sevierville combined statistical area reached approximately 1,156,861 in 2020. We present this range rather than resolve it, consistent with our approach to population data variance elsewhere in this series.
Employment & Labor Force
Knoxville added approximately 4,100 net jobs in 2025 (Yardi Matrix), with employment growth of 1.2% — double the 0.6% national rate — led by education/health services and government, while professional/business services, manufacturing, and construction each lost jobs. Unemployment stood at 2.9–3.2% depending on source, below both Tennessee (3.6%) and the U.S. (4.4%) rates.
Job Diversity & Industry
Anchored by the University of Tennessee, Knoxville (32,000+ enrollment, with record-breaking enrollment cited as a driver of past rent growth) and Oak Ridge National Laboratory, the U.S. Department of Energy’s largest science and energy research facility, located within the broader metro in Anderson County alongside the Y-12 National Security Complex. The metro also has a notable media and entertainment presence, historically home to Regal Entertainment Group’s headquarters. Tourism is a meaningful contributor, with the metro serving as a gateway to the Great Smoky Mountains and citing more than 14 million annual regional visitors in one source.
Fortune 500 Headquarters
We did not identify a Fortune 500 company currently headquartered in Knoxville. The metro’s economic weight instead comes from the University of Tennessee, Oak Ridge National Laboratory, and a diversified base of regional employers, rather than large corporate headquarters concentration.
Demographics & Renter Population
A renter base significantly shaped by the University of Tennessee’s more than 32,000 students, concentrated in and around the Downtown Knoxville submarket, alongside a broader population drawn by East Tennessee’s relative affordability and tourism-adjacent economy. Effective rents rose approximately 62% between the start of 2020 and late 2024, according to one regional housing forecast, notably outpacing the roughly 15% wage growth measured over a similar period — a genuine affordability
compression worth factoring into renter-income underwriting.
Crime & Livability Trends
Genuinely conflicting depending on methodology. One tracker using FBI Uniform Crime Reporting data found Knoxville’s overall crime rate running 25% below the national average and lower than 56% of comparably sized major U.S. cities. A separate tracker,
which compares Knoxville to all U.S. communities of all sizes rather than similarly populated cities, found Knoxville’s crime rate higher than 96% of Tennessee communities. We present both because they reflect genuinely different, defensible comparison methodologies rather than a simple factual dispute.
Overall, Knoxville combines a stabilizing university and national-laboratory-anchored economy with early, still-unconfirmed signs of a multifamily market inflection — a genuinely different stage of the cycle than the still-clearly-correcting or still-clearly-recovering markets elsewhere in this series.
Multifamily Metrics vs. National Benchmarks
Rent, Occupancy & Transaction Detail
Rent, Occupancy & Transaction Detail
Prior Quarterly Absorption
Knoxville’s most recent quarter looks meaningfully better than its trailing-year trend — a pattern this series has also seen, earlier in its development, in Tampa and Orlando. The combination of a 73% construction-starts collapse and a near-tripling of quarterly absorption is a genuine inflection signal, though one strong quarter should be treated as an early data point rather than a confirmed trend reversal.
Current & Future Trends
Rents and occupancy softened through 2025 and into early 2026, but Q2 2026 brought the first positive quarterly rent reading in a year and the strongest absorption quarter in two years.
New supply has concentrated in Western Knox County and North Knoxville, while Downtown Knoxville — anchored by the University of Tennessee
— has also absorbed significant recent deliveries given its proximity to campus.
2025 investment sales reached approximately $196 million, with average price per unit falling 6.2% to $132,648 — among the more affordable transaction bases in this series.
With construction starts down approximately 73%, supply should thin materially by late 2027, supporting continued improvement if the Q2 2026 trend holds through subsequent quarters.
Effective rents rose roughly 62% from 2020 to late 2024, notably outpacing wage growth over the same period, a genuine affordability compression worth monitoring in workforce-tier underwriting.
Continued investor interest should track the confirmation, or reversal, of the Q2 2026 inflection signals in subsequent quarterly data.
The University of Tennessee and Oak Ridge National Laboratory provide a demand base with limited correlation to the broader Sunbelt migration cycle affecting several other markets in this series.
Class C and select submarkets posted rent growth exceeding 5.0% annually even as the broader market stalled, suggesting demand remains
selectively strong beneath the metro-wide average.
Knoxville’s affordable per-unit basis, combined with
early recovery signals, may present a relative value entry point for investors comfortable underwriting a still-unconfirmed trend.
Market Projection — Five Years From Now (~2031)
Important Statistics Snapshot
Knoxville Multifamily Market
Construction starts decline, most recent reading — one of the sharpest in this series
−73%
Q2 2026 absorption — nearly 3x the prior quarter, strongest in two years
592 units
Average asking rent (source range)
~$1,430–1,470
Q2 2026 quarterly rent growth — first positive reading in a year
+1.9%
Average price per unit, Dec. 2025 — down 6.2%, an affordable basis for this series
~$132,648
Cap rates, across all asset classes combined
5.6–6.0%
Knoxville Economy Statistics
MSA population (source and definition dependent range)
~249,000 city /
~550,000 metro
University of Tennessee, Knoxville enrollment
2.7%
Unemployment Rate (May 2026 preliminary)
Job Growth: Modest recent (~0–1.1% YoY range in benchmarks); forecasted acceleration
Dropped by 18%
Homicide rate decline over four years
Dropped by 18%
Key Notes/Drivers: Logistics/distribution hub, film/entertainment (“Hollywood
of the South”), tech (“Silicon Peach”), corporate HQs, healthcare, and professional services. Diversified and resilient with strong historical job and population growth.
Main Companies & Market Players
Local & Regional
We did not identify a single, dominant Knoxville- headquartered multifamily developer comparable to the local anchors profiled in other editions of this series in our sourcing for this edition.
National Platforms
Recent notable deliveries include Church & Henley, a 237-unit Class A community near the University of Tennessee campus; development activity more broadly has concentrated in Western Knox County and North Knoxville.
Investors
2025 investment sales reached approximately $196 million, with per-unit pricing continuing to soften. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s supply cycle or industry base.
Submarket Intelligence
Near University of Tennessee
(Downtown-Adjacent)
Student-driven demand and record enrollment support strong absorption despite meaningful new supply, including recent Class A deliveries like the 237-unit Church & Henley.
Class C & Select Value-Tier Submarkets
Posted rent growth exceeding 5.0% annually even as the broader metro- wide market stalled, suggesting durable workforce-tier demand.
Western Knox County &
North Knoxville
Led all areas for new development and continue to carry the heaviest concentration of units under construction, representing the metro’s clearest near-term supply risk.
Data Note
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
In a Nutshell
Knoxville in 2026 is a market that softened through most of the past year but may be turning: construction starts have collapsed approximately 73%, and Q2 2026 brought both the first positive quarterly rent reading in a year and the strongest absorption quarter in two years. Whether this represents a genuine inflection or a single strong quarter within a still-soft trend remains to be confirmed. The University of Tennessee and Oak Ridge National Laboratory provide a demand base with real insulation from broader Sunbelt migration cycles, and an average price per unit near $132,648 offers one of the more affordable entry points in this series. Within a diversified Tennessee allocation, Knoxville pairs with Memphis and Nashville as a third, university- and national-laboratory-anchored complement.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.