Executive summary
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
Louisville, Kentucky serves as our twenty-fourth edition and the first Kentucky market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Louisville exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
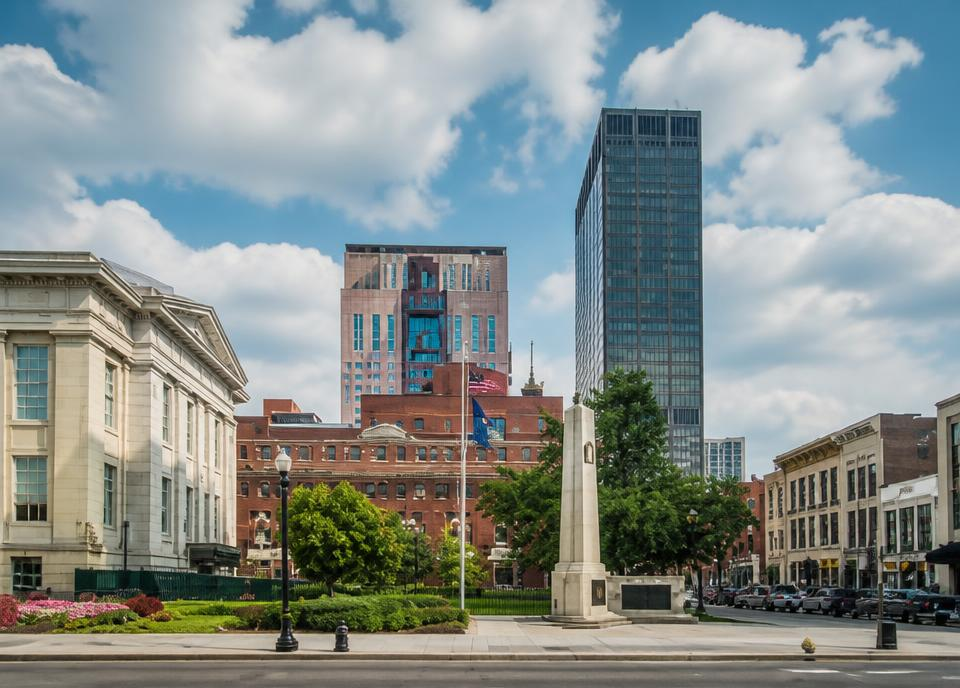
This Is What Louisville Looks Like
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report delivers an independent, data-driven assessment of the Charlotte multifamily sector as of mid2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
~$1,218–1,250
Average Rent per Unit
+0.7% to +2.5%
Rent Growth: Moderated From a2024 National-Leading Pace
~5.8%–8.9%
Overall Vacancy
669 units sold (Q1 2026)
Multifamily Deal Activity
~2,644–4,447 units
Units Under Construction
Sources: Yardi Matrix, CoStar Group, Marcus & Millichap. Data as of Q1–Q2 2026.
From National Rent-Growth Leader to Quietly Consistent Performer
Louisville held the top spot in Yardi Matrix’s national rent growth rankings in four of twelve months during 2024, with year-overyear growth peaking at 5.6% in July before ending the year at 4.3% — a genuinely unusual achievement for a market of Louisville’s size. Rent growth has since moderated materially, to approximately 0.7% (Yardi, October 2025) to 2.5% (a separate source) — still modestly ahead of the national average in most readings.
Stabilized occupancy has held remarkably steady, not falling below 93% since 2022 and standing at approximately 93.5–93.8% in the most recent readings even amid record local deliveries. Average effective rents of approximately $1,218–$1,250 remain firmly in the affordable tier nationally, and new supply additions dropped to their lowest level in eight years in one 2025 reading, even as a separate, larger reading cited a substantial 24,589-unit longer-term development pipeline.
Current indicators point to a market that avoided both overheating and overcorrection:
- Net absorption over the trailing 12 months totaled 3,667 units, up from 2,590 the prior year — a gain of more than 1,000 units suggesting renter demand is accelerating, not merely keeping pace.
- Stabilized occupancy has not fallen below 93% since 2022, even through a period of record local deliveries.
- Louisville ranks as the 54th-largest multifamily market in the U.S., with a substantial 24,589-unit longer-term development pipeline signaling continued developer confidence.
- Investment activity remained steady but selective, with 669 units sold in Q1 2026 and cap rates held stable even as the 10-Year Treasury rate declined.
Within the Longview portfolio, Louisville reads as a genuinely defensive, income-oriented holding: a market defined by consistency rather than volatility, appropriate for investors prioritizing dependable cash flow over rapid appreciation.
General Metro Louisville Metrics
Economy & Demographics
Population figures show a notable spread depending on source and vintage. MacroTrends cited a Louisville MSA population of approximately 1,136,000 in 2025, growing a steady 0.81–0.9% annually in recent years, while older Wikipedia-sourced figures cite a considerably higher 2020 MSA population near 1.36–1.4 million — a discrepancy likely reflecting different data vintages or geographic definitions that we flag rather than resolve. The consolidated Louisville/Jefferson County metro government reported approximately 622,981 residents in 2025, while Jefferson County itself saw a slight population decline of approximately 0.12% from 2024 to 2025, even as the broader MSA continued growing modestly.
Employment & Labor Force
Louisville is projected to add approximately 8,000-10,000 jobs in 2026, per one regional lending-market source. Unemployment stood at 4.6% at the end of February 2026, matching the Q1 2025 rate after a brief decline in Q3 2025 —a relatively flat, if not accelerating, labor-market trend.
Job Diversity & Industry
A diversified economy anchored by healthcare, logistics, and consumer brands. UPS operates its global air hub, Worldport, at Louisville’s airport — one of the largest package-handling facilities in the world — though UPS’s corporate headquarters remains in Atlanta. Louisville is home to Humana (health insurance), Yum! Brands (parent of KFC, Taco Bell, and Pizza Hut), and BrownForman (spirits, including Jack Daniel’s and Woodford Reserve), among other major employers. The metro’s bourbon and distilling heritage continues to support tourism and hospitality demand alongside its logistics and healthcare base.
Fortune 500 Headquarters
Louisville is home to Fortune 500 headquarters including Humana and Yum! Brands, alongside Brown-Forman, a major publicly traded spirits company also headquartered in the metro. This is a genuine, if more concentrated, corporate anchor base relative to some other markets in this series, distinct from UPS’s large Worldport employment presence, which is not a headquarters function.
Demographics & Renter Population
A renter base supported by steady, if unspectacular, population growth and Louisville’s position as a national logistics and healthcare hub. The metro’s affordability — average rents in the $1,218–$1,250 range, well below national averages — continues to attract and retain a stable, long-term tenant pool, a dynamic multiple sources specifically cited as a structural demand driver for the market.
Crime & Livability Trends
A now-familiar pattern in this series: one tracker comparing Louisville to all U.S. communities of all sizes found a crime rate higher than 99% of Kentucky communities, while the same source noted that, compared specifically to similarly sized communities nationally, Louisville’s crime rate runs close to the average — not notably more or less dangerous than would be expected for a metro of its size. We present both framings given the genuinely different, defensible comparison methodologies involved.
Overall, Louisville combines a demonstrated ability to lead the nation in rent growth during periods of strength with an equally notable ability to avoid overcorrection afterward — a consistency this series has associated more with defensive holdings like Columbia and Richmond than with higher-amplitude Sunbelt growth markets.
Multifamily Metrics vs. National Benchmarks
Rent, Occupancy & Transaction Detail
Rent, Occupancy & Transaction Detail
2025 12-Month Absorption
3,667 units
Prior 12-Month Absorption
Louisville’s trajectory in this series is genuinely unusual: few markets lead the nation in rent growth during a strong period and then moderate gracefully, without the sharp reversal or oversupply hangover seen in markets like Austin or San Antonio. Louisville’s affordability, steady absorption acceleration, and consistently sub-7% stabilized vacancy since 2022 all point to a market whose 2024 strength reflected durable, broad-based demand rather than a speculative supply-demand imbalance.
Current & Future Trends
Louisville led national rent growth rankings for four months in 2024 before moderating to a steadier, still above national pace through 2025 and into 2026, with stabilized occupancy holding above 93% throughout.
The Indiana side of the metro recorded more than 5% annual inventory growth since 2022 — the fastest of any submarket — yet vacancy there has held near 4%, among the lowest in the metro, a genuine bifurcation of heavy supply and equally heavy absorption.
Investment activity remained modest but steady, with cap rates held stable by selective Treasury rates declined over the same period.
With new supply additions reported at an eight-year low in one 2025 reading, and a substantial longer-term pipeline still in the planning stages, the near-term supply outlook should remain manageable relative to demand.
A similar new-supply pullback is expected in Southwest Louisville in 2026, while Okolona and Jeffersontown lead future pipeline activity and represent the metro’s clearest near-term supply-risk concentration
Continued absorption acceleration (3,667 units over the trailing year, up from 2,590 the year prior) should support increased investor confidence as 2026 progresses.
Humana, Yum! Brands, Brown-Forman, and UPS Worldport’s massive logistics employment provide a diversified demand base spanning healthcare, consumer brands, and distribution.
Submarket-level performance suggests Louisville’s overall stability is broad-based rather than concentrated in a single high-performing corridor
Louisville’s status as the nation’s 54th-largest multifamily market, combined with its demonstrated stability, may appeal to investors specifically seeking lower-volatility exposure within a broader portfolio.
Market Projection — Five Years From Now (~2031)
Important Statistics Snapshot
Charlotte Multifamily Market
Louisville led the nation in Yardi Matrix’s rentgrowth rankings during 2024
4 of 12 months
Stabilized occupancy has not fallen below this level since 2022
93% +
Vacancy (source-dependent range)
~5.8%–8.9%
Average effective rent—firmly in the national affordable tier
~$1,218–1,250
Trailing 12-month absorption, up from 2,590 the prior year
3,667 units
Louisville’s national rank by multifamily market size
54th
Cap rates: stable commercial real estatedepending on the asset class
5.5% to 8%
Charlotte Economy Statistics
Population — older sources cite a notably higher ~1.36–1.4M for 2020 (see report text)
~2.3–2.9M metro
Fortune 500 headquarters — Humana, Inc. and Yum! Brands, alongside Brown-Forman and UPS.
~4.3%
Unemployment Rate: Low-to-moderate
~1.4%
Job Growth has softened to a modest pace
+33,900 jobs
Homicide rate have dropped significantly, compared to prior-year periods
−25%
Key Notes/Drivers: Logistics (major UPS hub), healthcare, manufacturing (automotive/food & beverage), and tourism (bourbon/
Main Companies & Market Players
Local & Regional
We did not identify a single, dominant Louisville headquartered multifamily developer comparable to the local
anchors profiled in other editions of this series in our sourcing for this edition.
National Platforms
Development activity has concentrated on the fast-growing Indiana side of the metro and in Southwest Louisville, while Okolona and Jeffersontown lead future planned pipeline activity
Investors
Investment activity remained modest but steady into 2026, with 669 units sold in Q1 2026 and cap rates held stable by selective investors despite declining Treasury rates. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s growth rate or volatility profile.
Submarket Intelligence
Indiana Side (Southern Indiana)
Recorded more than 5% annual inventory growth since 2022 — the fastest in the metro — yet vacancy has held near 4%, among the lowest readings, with the delivery pipeline now contracting sharply.
Southwest Louisville
A similar new-supply pullback is expected here in 2026, mirroring the Indiana side’s pattern of absorbing heavy recent supply before a construction pause.
Okolona & Jeffersontown
Lead future planned pipeline activity, representing the metro’s clearest concentration of near-term supply risk.
Data Note
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
In a Nutshell
Louisville in 2026 offers a genuinely distinctive track record in this series: a market that led the nation in rent growth during four months of 2024, then moderated gracefully rather than reversing sharply, with stabilized occupancy that has not fallen below 93% since 2022. Structural affordability, accelerating absorption, and a diversified corporate base (Humana, Yum! Brands, Brown Forman, and UPS Worldport’s massive logistics presence) support a constructive, if unspectacular, long-term view. Within a diversified allocation, Louisville pairs with Columbia and Richmond as a defensive, income-oriented holding, distinguished by its demonstrated ability to avoid the boom-bust pattern several faster-growing Sunbelt metros in this series have experienced.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.