
Mobile is genuinely different from every other market in this series — not because its fundamentals are weaker or stronger, but because the institutional data infrastructure that grounds the rest of this series simply does not cover it. That gap is the finding.
August 2026
Mid-2026 Outlook
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
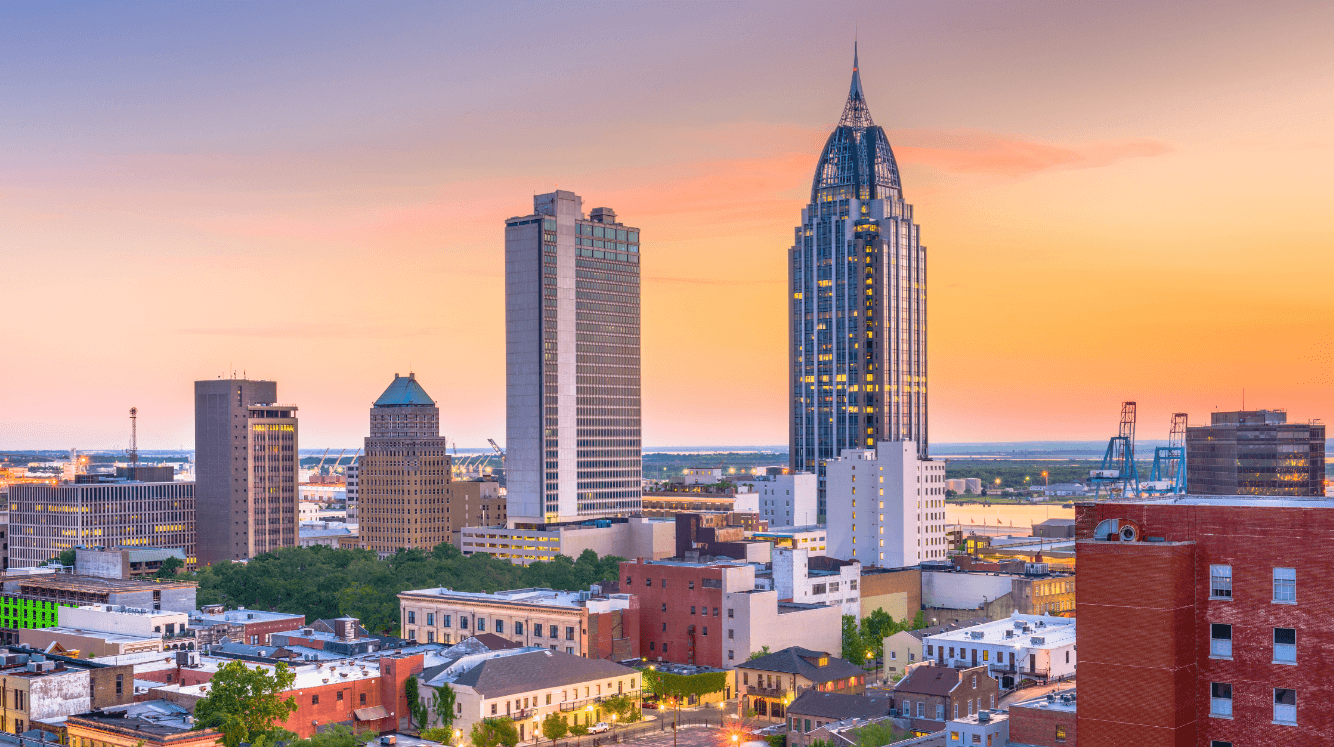
Mobile, Alabama serves as our fourteenth edition and the first market in this series without institutional-grade multifamily data coverage in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Mobile exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and
sophisticated investors. This report is different from the other thirteen editions in this series: Mobile falls below the coverage threshold of the major commercial real estate research platforms (Yardi Matrix, CoStar, MMG Real Estate Advisors, Matthews, Northmarq) that ground every other report in this series. What follows is an honest account of what is and is not knowable about this market from public sources today.
Sources: U.S. Census Bureau, Federal Reserve Bank of St. Louis. Data as of Q1–Q2 2026.
Every other market in this series — including small secondary markets like Birmingham and Memphis — has at least one, and
usually several, institutional-grade multifamily data sources publishing current rent, vacancy, construction, and transaction
figures. For Mobile, we identified none. Multiple targeted searches across the CRE research platforms used throughout this series (Yardi Matrix, CoStar-sourced reports, MMG Real Estate Advisors, Matthews, Northmarq) returned no dedicated Mobile MSA multifamily coverage.
This is very likely a function of scale: Mobile’s metropolitan population (approximately 335,000–430,000, depending on geographic definition) sits below the threshold most major CRE research platforms use to justify dedicated quarterly coverage. What we can responsibly report here is macroeconomic and demographic context from public federal sources — population, employment, and major-employer data — alongside a clear recommendation that any specific multifamily underwriting in this market be grounded in direct broker opinions of value, property management surveys, and local tax-assessor records rather than the kind of institutional dataset this series otherwise relies on.
Within the Longview portfolio, Mobile cannot currently be evaluated on the same evidentiary basis as the other thirteen markets in this series. We present this edition as a demonstration of our sourcing discipline: rather than approximate figures to preserve a consistent report format, we are telling you plainly what is and is not knowable from the sources available to us today.
The City of Mobile’s population has been declining: approximately 199,600 as of 2026, down from 206,485 at the 2020 Census (a 3.33% decline), continuing at a rate of roughly −0.61% annually. The broader Mobile metropolitan statistical area, Alabama’s third-most-populous metro, reached approximately 335,000–430,000 depending on geographic definition (sources
vary between core-MSA and combined-area figures), growing only marginally in recent years. This is a materially different demographic trajectory than any other market profiled in this series to date.
Mobile MSA unemployment stood at 3.8% in 2024, below the 4.1% national average. Employment grew approximately 1.5% from 2023 to 2024, with the strongest gains in construction (+5%, driven by infrastructure projects and post-storm rebuilding) and professional/business services. Average annual wages reached approximately $55,000 in 2024 (a mean hourly rate of $26.20), below the levels seen in several other markets in this series.
Mobile’s economy centers on maritime and aerospace manufacturing. Austal USA, a shipbuilder specializing in aluminum and steel vessels for the U.S. Navy, is the city’s largest industrial employer. The Mobile Aeroplex at Brookley hosts more than 70 companies across 1,650 acres, anchored by Airbus’s only U.S. final assembly line (producing the A220 and A320 family aircraft), alongside VT Mobile Aerospace Engineering and Continental Motors. The Port of Mobile, Alabama’s only deep-water port and the nation’s 12thlargest by tonnage, supports a substantial logistics and distribution sector, including major import operations for national retailers.
We did not identify any Fortune 500 companies headquartered in Mobile in our sourcing for this edition. The metro’s major employer base is instead anchored by large industrial operations (Austal USA, Airbus, VT Mobile Aerospace Engineering) rather than corporate headquarters — a meaningfully different economic profile than the larger metros in this series.
Mobile’s median household income is approximately $53,600–$55,900 depending on source, with a poverty rate of approximately 18.4–19.2% — the most economically constrained renter base of any market profiled in this series to date. Housing costs are low on an absolute basis (median home value approximately $195,000–$260,000 across sources), consistent with the metro’s below average wage levels.
The multifamily real estate landscape in Mobile, Alabama is being heavily reshaped by a distinct divergence between historical crime perceptions and actual 2026 downward crime trends, alongside aggressive public livability investments. For real estate investors and developers, understanding these neighborhood dynamics is key to predicting long-term demand shifting across the metro. Homicides fell by 15.8 percent from 2024 to 2025. Sexual assaults were down by 31.9 percent. Robbery, aggravated assault and larceny all experienced double-digit percentage decreases.
Overall, Mobile presents a genuinely different profile than any other market in this series: a declining core city population, a slow growing metro, a below-average wage base, and — centrally — an absence of the institutional multifamily data infrastructure this series otherwise relies on.
2025 Full-Year Volume
$95-$135 M
YTD Through March 2026
~$18.5 M
Mobile’s absence from institutional multifamily research coverage is itself informative: it signals a market that has not attracted the sustained institutional capital flows that generate ongoing data coverage, in contrast to every other metro in this series. This does not mean the market lacks investment merit, but it does mean that any Mobile-specific multifamily thesis would need to be built from primary research (broker opinions of value, property manager surveys, county tax-assessor data) rather than the syndicated institutional data this series otherwise relies on.
CURRENT (2026)
Population trends are a genuine near-term headwind: the core city
is declining and the broader metro is growing only marginally, a materially weaker demographic setup than any other market in this
series.
No institutional multifamily data source was identified to characterize current supply, demand, or pricing dynamics specific to this market.
Post-storm rebuilding and infrastructure investment have been a meaningful, if temporary, driver of recent construction- sector employment growth.
5-YEAR OUTLOOK ( 2031)
Employment and wage data show modest, steady improvement, but starting from a lower wage base
than the metros covered elsewhere in this series.
Any near-term view of Mobile’s multifamily fundamentals would need to be built from direct broker relationships and primary market research rather than syndicated institutional data.
The durability of this growth driver beyond the current infrastructure cycle is not established in the sources reviewed for this edition.
10-YEAR OUTLOOK
The Port of Mobile, Airbus, and Austal USA provide a durable industrial and logistics employment anchor largely uncorrelated with the population-growth stories driving several other markets.
A future edition of this report, informed by direct market engagement, could meaningfully upgrade the evidentiary basis for a Mobile investment thesis.
Aerospace and maritime manufacturing (Airbus, Austal USA) represent the more structural, longer duration component of Mobile’s economic base.
Recent inventory growth over three years, now normalizing
4.0%
Under construction
~450 – 600 Units
Stabilized occupancy
94.6% – 95.0%
Average asking rent
~$1,131
Projected 2026 rent growth
4.0%
Cap rates, generally
5.20% to 5.80%
City of Mobile population, 2026 — declining from 206,485 in 2020
~199,600
Metro population (source-dependent
geographic definition), slow-growing
~335,000 – 430,000
Unemployment Rate: Higher than state average (state AL ~3.0%; metro typically elevated)
~3.0%
Job Growth: Variable/Moderate (+1.5% MSA employment growth, 2023–2024)
+1.5%
Homicide rate decline from 2024 and 2025
-15.8%
Key Notes/Drivers: Port/shipping/logistics, aerospace/manufacturing, and healthcare. Smaller scale with industrial focus.
We did not identify a dominant, Mobile head quartered multifamily developer comparable to the local anchors profiled in other editions of this series (e.g., MAA in Memphis, Daniel Corporation in Birmingham) in our sourcing for this edition.
We recommend direct outreach to regional
Gulf Coast brokerage and development platforms for current, on-the-ground intelligence on active Mobile multifamily developers and owners, rather than relying on the secondarysources available for this report.
We did not identify institutional capital-flow data specific to Mobile multifamily assets in our sourcing for this
edition. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily exposure grounded in verifiable data — a standard this particular market does not yet allow us to meet with secondary sources alone.
Submarket
Profile & Theme
Longview View
Midtown & Spring Hill
Commonly cited in consumer-facing sources as established, desirable residential neighborhoods, though we could not verify institutional-grade multifamily performance data for these areas specifically.
Exploratory
West Mobile
Referenced as a growing residential corridor in consumer sources, again without verifiable institutional multifamily data to support a specific investment view.
Exploratory
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
Mobile in 2026 is a market we cannot currently evaluate on the same evidentiary basis as the other thirteen editions in this series. No institutional multifamily data source in our review covers this metro’s rent, vacancy, construction, or transaction fundamentals. What public federal data does show is a genuinely different profile than any other market Longview has profiled to date: a declining core city population, marginal metro growth, and a below-average wage base, offset by durable industrial anchors in the Port of Mobile, Airbus, and Austal USA. We are publishing this edition specifically to demonstrate our sourcing discipline — we do not manufacture the appearance of data-driven precision where the underlying data does not exist. Any Mobile-specific investment thesis should be grounded in direct, commissioned primary research before proceeding.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.
Website: www.longviewcommercial.com