
“Hampton Roads posted the third-highest annual apartment rent growth among the nation’s top 50 markets, with only 648 units under construction — 0.5% of total inventory. The world’s largest naval base does not care about interest rate cycles the way most Sunbelt demand drivers do.”
August 2026
Mid-2026 Outlook
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to
share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
Norfolk/Virginia Beach, Virginia serves as our twenty-third edition and the second Virginia market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Norfolk/Virginia Beach exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and
sophisticated investors. This report delivers an independent, data-driven assessment of the Norfolk/Virginia Beach (Hampton Roads) multifamily sector as of mid-2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
Sources: Northmarq, Newmark, CoStar Group. Data as of Q1–Q2 2026.
Hampton Roads posted effective rent growth of approximately 4.1% year-over-year as of Q1 2026 — the third-highest annual
apartment rent growth among the top 50 U.S. markets, per Newmark — while vacancy ran approximately 5.2– 6.2%, meaningfully below the roughly 8.6% national average cited by CoStar-sourced data. This is among the tightest, best-performing multifamily markets of any profiled in this series.
Within the Longview portfolio, Hampton Roads offers a genuinely different demand anchor than any other market in this series: the world’s largest naval base and a Fortune 500 shipbuilder, both of which generate demand with limited correlation to broader economic or interest-rate cycles
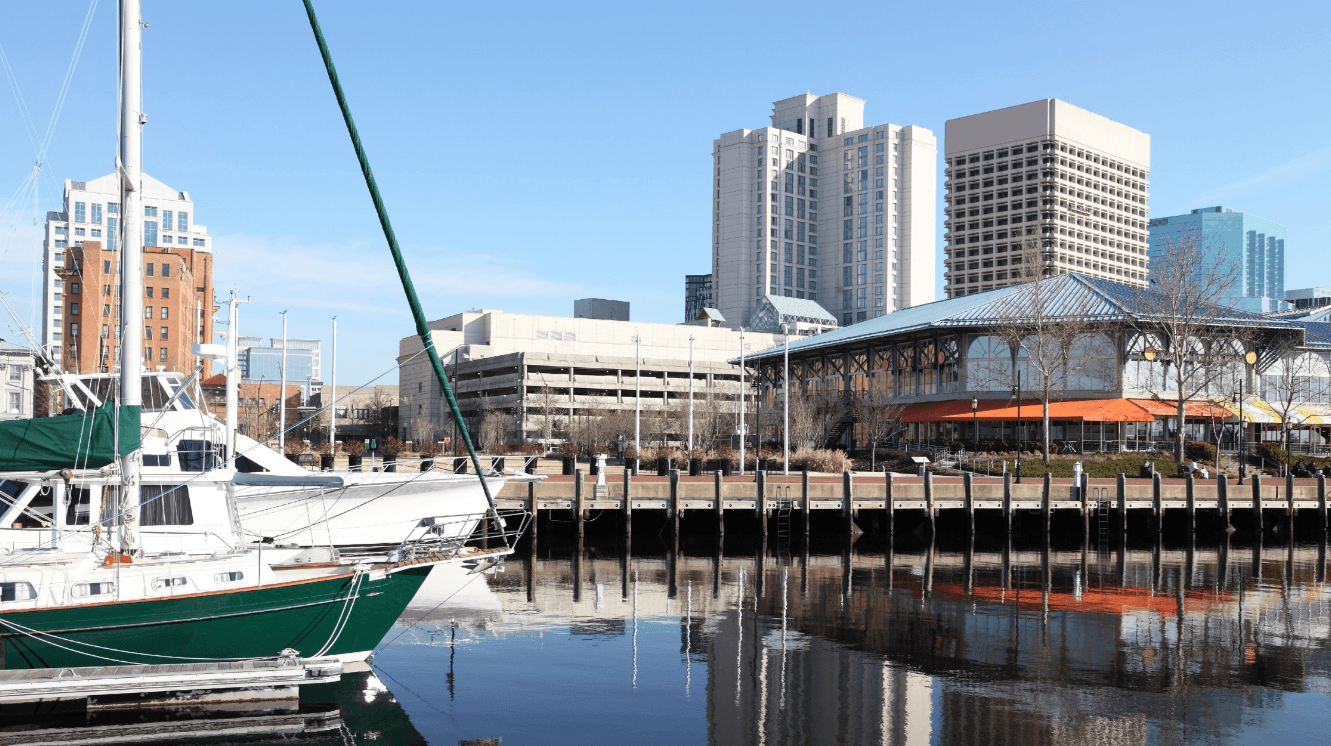
The Virginia Beach-Norfolk-Newport News, VA-NC metropolitan statistical area reached approximately 1.78–1.79 million residents as of 2023 estimates, with the broader combined statistical area (including additional North Carolina counties) reaching approximately 1.89 million. This is among the larger metro populations of any market profiled in this series, though growth has historically been steadier than the faster-growing Sunbelt metros elsewhere in this report series.
We did not identify a current, precise metro-wide employment growth percentage with the same rigor available for several other markets in this series. Available data indicates a median household income across the broader MSA of approximately $79,325, reflecting a mix of defense-related professional salaries and service-sector wages, with individual cities like Norfolk reporting notably lower figures (approximately $62,382)
Anchored by the U.S. Navy’s largest base, Naval Station Norfolk, home to the world’s largest concentration of naval assets and the hub of the Atlantic Fleet. Virginia Beach hosts Naval Air Station Oceana (the city’s largest employer) and Naval Amphibious Base Little Creek, both considered the largest of their respective kinds in the world. Newport News Shipbuilding, a division of Huntington Ingalls Industries, is the only U.S. shipyard capable of building nuclear-powered aircraft carriers and represents one of the region’s largest industrial employers. The Port of Virginia adds a substantial maritime logistics component.
Huntington Ingalls Industries, the parent company of Newport News Shipbuilding and the nation’s largest military shipbuilder, is headquartered in Newport News, within the Hampton Roads metro — a genuine Fortune 500 anchor for this market, distinct from several other secondary markets profiled in this series where no such headquarters was identified.
A renter base heavily shaped by military personnel and their families, with peak Permanent Change of Station (PCS) season each summer driving a pronounced seasonal surge in relocations that fills vacancies largely independent of broader economic conditions. Neighborhoods near major installations, including areas north of I-264 in Virginia Beach, draw particularly strong and consistent demand from military families.
A genuinely bifurcated picture across the metro’s constituent cities. Norfolk specifically was ranked among the nation’s worst for rising homicide rates in one 2026 analysis (8th nationally), earning an overall crime grade of C- from one tracker and prompting a state-level crime-reduction initiative announced in the city. Virginia Beach and Chesapeake, by contrast, ranked far lower on the same rising- homicide list (34th and 49th respectively) with each reporting fewer than 20 homicides for the year — a meaningfully safer profile. Investors should treat Hampton Roads as multiple distinct cities from a safety-underwriting perspective rather than a single uniform metro.
Overall, Hampton Roads combines one of the tightest, best-performing multifamily markets in this series with a defense- and shipbuilding-anchored demand base that behaves differently across economic cycles than most other markets Longview tracks — balanced against genuinely uneven public-safety conditions between its constituent cities.
Units Under Construction
~648 (0.5% of stock)
2025 Deliveries
~2,250 units
Hampton Roads stands out in this series as one of the tightest, most defense-insulated multifamily markets Longview tracks.
Where most markets in this series are working through some version of a recent supply wave, Hampton Roads enters 2026 with almost no construction pipeline at all (0.5% of inventory), a genuinely rare position that reflects both the market’s historically measured development pace and a demand base — anchored by the world’s largest naval base — with limited correlation to broader economic cycles.
CURRENT (2026)
Vacancy of approximately 5.2–6.2% sits meaningfully below
the national average, with most major submarkets achieving
vacancy declines exceeding 100 basis points in 2025.
Norfolk City led both absorption (527 units, 2.0% of inventory) and rent growth (+4.8%) among tracked submarkets, while
Virginia Beach led investment volume ($267 million) and commanded the highest rent levels.
Median sale price rose approximately 30% yearover-year to $161,500 per unit, with cap rates holding in a tight 5.25– 5.5% range even as varied by reporting
5-YEAR OUTLOOK ( 2031)
With only 0.5% of inventory currently under construction and permitting already pulling back
further, supply pressure should remain minimal through the remainder of 2026 and into 2027.
The heavy-industry-oriented Newport News submarket saw net absorption turn negative in late 2025, a notable exception to the broader market’s strength.
Deal flow has been relatively balanced across Chesapeake, Newport News, Norfolk City, and Virginia Beach, suggesting broad-based rather than narrowly concentrated investor interest.
10-YEAR OUTLOOK
Naval Station Norfolk, NAS Oceana, and Huntington Ingalls Industries’ shipbuilding operations provide a demand base with limited correlation to broader economic or interest-rate cycles.
Peak military Permanent Change of Station season each summer drives a pronounced, largely economically- independent seasonal surge in leasing activity, particularly in neighborhoods near major installations.
The combination of tight vacancy, strong rent growth, and a minimal construction pipeline supports a constructive near term pricing environment for well-located, stabilized assets
Units under construction as a share of total inventory — among the lowest in
this series
0.5%
2025 deliveries, consistent across
independent sources
~2,250 units
Vacancy —meaningfully below the ~8.6%
national average
~5.2%–6.2%
Average/median rent(source and propertytype-dependent range)
~$1,650–1,934
Rent growth, year-over-year— 3rd- highest
among the top 50 U.S. metros
+3.0% to +4.2%
Median sale price per unit, up ~30% yearover-year
~$161,500
Cap rates strong asset pricing and
performance in Class C properties
5.6%
Metro population (MSA vs. broader CSA
definitions)
~1.78–1.89M
Fortune 500 headquarters — Dollar Tree,
Ferguson Enterprises, Huntington Ingalls
Industries
3
Unemployment Rate
~3.9%
Job Growth: dip in overall nonfarm employment
1.4%
Homicide rate year-over-year increase in
homicides
64%
Key Notes/Drivers:Military (large Navy presence), port/logistics, tourism,
healthcare, and shipbuilding. Defense and maritime economy dominate.
We did not identify a single, dominant Hampton Roads-headquartered multifamily developer comparable to the local anchors profiled in other editions of this series in our sourcing for this edition
Deal flow across the metro has been relatively balanced among Chesapeake, Newport News, Norfolk City, and Virginia Beach, suggesting broad-based rather than concentrated developer and investor activity.
Cap rates have held in a tight 5.25–5.5% range, with Class A product trading near the lower end and Class B/C assets clustering closer to 5.5%, signaling continued investor competition for well-located, stabilized communities. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s demand driver or economic base.
Submarket
Profile & Theme
Longview View
Virginia Beach
Leads investment volume ($267 million) and commands the metro’s highest rent levels, with vacancy near 3% in December — among the tightest readings in this entire series. Also the safer of the metro’s two largest cities
by recent crime trend.
Favorable
Norfolk City
Leads absorption (527 units, 2.0% of inventory) and rent growth (+4.8%) among tracked submarkets, though the city carries a genuinely elevated public-safety risk profile requiring separate underwriting attention.
Selective
Chesapeake
Offers a strong combination of occupancy and rent-growth momentum in the workforce-housing (3-Star/Class B) segment specifically
Selective
Newport News
The metro’s heavy-industry-oriented submarket saw net absorption turn negative in late 2025, a notable exception to the broader market’s strength.
Cautious
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
Hampton Roads in 2026 is one of the tightest, best-performing multifamily markets in this series: vacancy well below the national average, rent growth ranking third-highest among the nation’s top 50 metros, and a construction pipeline representing just 0.5% of total inventory. The world’s largest naval base and a Fortune 500 shipbuilder anchor a demand base with genuine insulation from broader economic cycles, though investors should treat this metro as several distinct cities rather than one uniform market — Norfolk’s public- safety profile diverges sharply from Virginia Beach’s and Chesapeake’s, and Newport News has shown recent softness even as the broader metro remains strong.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.
Website: www.longviewcommercial.com