Executive summary
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic
momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to
share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
Oklahoma City, Oklahoma serves as our twenty-fifth edition and the first Oklahoma market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Oklahoma City exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid 2026 assessment.
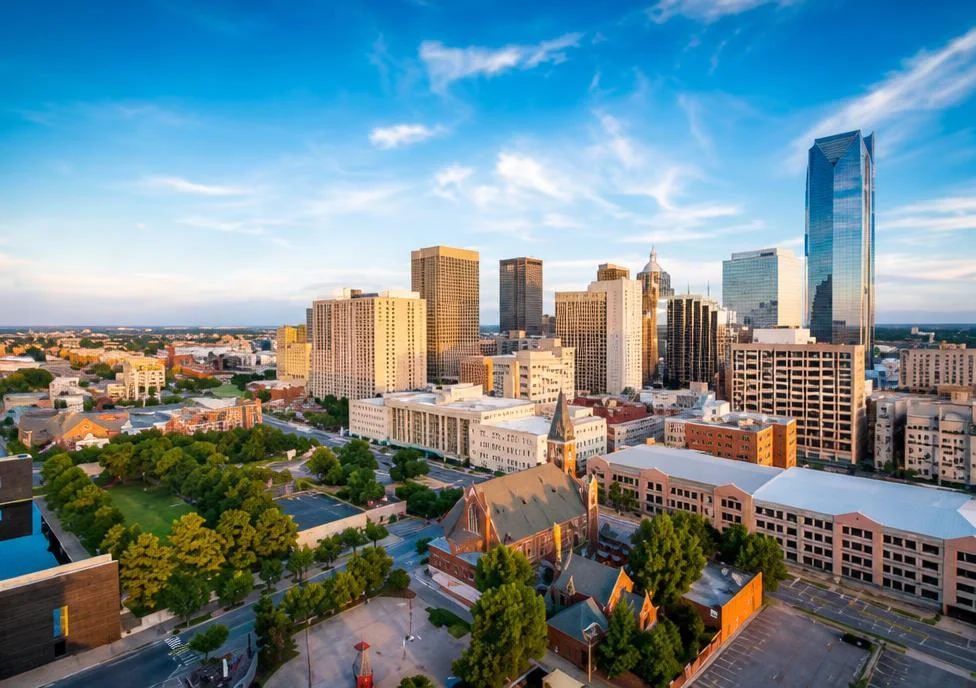
This Is What Oklahoma City Looks Like
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report delivers an independent, data-driven assessment of the Oklahoma City multifamily sector as of mid-2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
~$1,060–1,238
Average Rent per Unit
+2.0% to +3.5% (region) / −0.7% (OKC, Q4 2025)
Rent Growth: Positive Annually, But a Recent Quarterly Dip
~4.8%–5.2%
Overall Vacancy
Median $60,700/unit — the lowest basis in this series
Multifamily Deal Activity
300 units (Q1 2026, −60%+ permits vs. 2024)
Units Under Construction
Sources: Northmarq, CoStar Group. Data as of Q1–Q2 2026.
The Lowest Price Basis in This Series, With a Construction Pipeline to Match
Oklahoma City (combined with Tulsa in most regional reporting) posted vacancy of just 4.8% in Q1 2026, down year-over-year even as rent growth continued in the 2.0–3.5% range regionally. New multifamily deliveries have nearly stopped: developers completed roughly 3,700 units in 2024, 2,200 in 2025, and just 300 in Q1 2026, while permits fell more than 60% between 2024 and 2026.
OKC-specific, more granular data shows a genuine recent counter-signal worth flagging directly: Q4 2025 saw net absorption turn negative (−23 units) for the first time since Q4 2023, with occupancy declining across every property class except Class C and average rent dipping slightly from $1,067 to $1,060. This should be read as an early signal to monitor, not dismissed.
Current indicators point to a structurally tight market with one recent soft data point:
- New multifamily construction permits fell more than 60% between 2024 and 2026, leaving OKC its thinnest construction pipeline in over a decade.
- Median multifamily sale price of $60,700 per unit (down 5% from 2025) is dramatically below every other market profiled in this series to date.
- Q4 2025 brought the first negative quarterly absorption reading since Q4 2023, alongside occupancy declines across most property classes.
- The metro added approximately 8,300 residents early in the year, with in-migration cited from higher-cost markets including Dallas and Denver
Within the Longview portfolio, Oklahoma City is the most explicitly deep-value market in this series after Birmingham: a low entry basis and constrained supply pipeline balanced against a market smaller and less liquid.
General Metro Oklahoma City Metrics
Economy & Demographics
Population figures show some variance by source. Macro Trends cited the Oklahoma City metro population at approximately 1,018,000 in 2023, growing roughly 1% annually, while a less rigorously sourced estimate cited a considerably higher figure near 1.5 million — a discrepancy we flag rather than resolve, weighting MacroTrends as more reliable. The City of Oklahoma City reached approximately 697,000–720,000 residents depending on source, the state’s most populous city, growing at an estimated 1.7% annual rate.
Employment & Labor Force
We did not identify a current, precise metro-wide employment growth percentage with the rigor available for larger markets in this series. Oklahoma City has historically been cited for economic stability, including a prior ranking as the U.S. metro with the lowest unemployment rate, though these specific rankings reflect data from several years prior and should be treated as directional context.
Job Diversity & Industry
A diversified economy anchored by aerospace/defense, energy, healthcare, and education. Tinker Air Force Base, the second largest military air depot in the nation, is the metro’s largest single-site employer with more than 24,000 military and civilian personnel. Oklahoma City is also a genuine energy-sector hub, home to Devon Energy (whose headquarters tower is the tallest building in the state) and Chesapeake Energy. OU Health (9,000+ employees) and the University of Oklahoma (6,000+ faculty and staff) anchor healthcare and education employment.
Fortune 500 Headquarters
Devon Energy Corporation, headquartered in Oklahoma City, is a Fortune 500 company and the metro’s most prominent corporate headquarters. Chesapeake Energy Corporation is also headquartered in the metro as a major energy-sector employer, though we did not confirm its current Fortune 500 status given fluctuating energy-sector revenues year to year.
Demographics & Renter Population
A renter base supported by strong housing affordability relative to home-ownership costs, with the metro specifically cited as drawing in-migration from higher-cost markets including Dallas and Denver. Downtown one-bedroom units average approximately $1,350 per month, above the broader metro average, reflecting urban-core demand distinct from the wider market.
Crime & Livability Trends
A moderate, unremarkable picture by the standards of this series. One tracker assigned Oklahoma City an overall crime safety grade of C+ as of 2026, with crime running approximately 1% below the national average and lower than 33% of major U.S. cities. Safety varies significantly by neighborhood, with roughly 84% of tracked neighborhoods rated A or B for safety.
Overall, Oklahoma City combines an exceptionally low cost basis, durable defense and energy-sector employment anchors, and one of the most constrained construction pipelines of any market in this series — balanced against a recent, genuinely soft quarterly data point and a smaller, less liquid transaction market than the larger metros this series otherwise covers.
Multifamily Metrics vs. National Benchmarks
Rent, Occupancy & Transaction Detail
Rent, Occupancy & Transaction Detail
2024 Deliveries (Regional)
Q1 2026 Deliveries (Regional)
Oklahoma City’s combination of an exceptionally low per-unit cost basis ($60,700, versus $119,000–$326,000 across other markets in this series) and one of the most constrained construction pipelines Longview tracks is genuinely distinctive. Consistent with how we framed Birmingham, the open question is whether this reflects durable relative value or thinner institutional capital flows — both readings are defensible, and underwriting should test both.
Current & Future Trends
Vacancy held tight at 4.8% regionally in Q1 2026, even as OKC specific Q4 2025 data showed a genuine softening — negative absorption and occupancy declines across most classes.
OKC holds 59% of the region’s multifamily inventory, yet sales activity has split roughly evenly with the smaller Tulsa market, which reportedly draws disproportionate investor interest.
Transaction velocity fell sharply (54% from 2024 to 2025, a further 17% in Q1 2026), with median pricing continuing to soften to $60,700 per
With construction permits down more than 60% since 2024, the supply backdrop should continue supporting occupancy even if the Q4 2025 softening persists another quarter or two.
Continued in-migration from higher-cost markets like Dallas and Denver should support demand, though population data itself shows source-to-source variance worth confirming directly.
Cap rates of 6.5–7.0% reflect value-oriented pricing and a wider spread than several larger, more liquid markets in this series.
Tinker Air Force Base’s 24,000+ employees and the metro’s energy-sector anchors provide demand drivers with limited correlation to broader migration cycles.
Downtown OKC commands a premium over the broader metro average, suggesting genuine urbancore demand distinct from the wider market’s value-oriented positioning.
Whether continued softening represents a buying opportunity or thin institutional interest should be tested directly with local brokerage sources.
Market Projection — Five Years From Now (~2031)
Important Statistics Snapshot
Charlotte Multifamily Market
Construction permits, 2024 vs. 2026 — lowest
pipeline in over a decade
−60%+
Q1 2026 regional deliveries, down from ~3,700 in 2024
300 units
Vacancy—tight by national standards
~4.8%–5.2%
Average rent (source and class- dependent range)
~$1,060–1,238
Q4 2025 net absorption — first negative
quarter since Q4 2023
−23 units
Median sale price—the lowest basis of any market in this series
$60,700/unit
Average apartment cap rates have mostly flattened out and stabilized between
6.2% and 6.8%
Charlotte Economy Statistics
Population — see report text for a notable source discrepancy
~1.02M (MacroTrends) / city ~697K–720K
Fortune 500 headquarters — Devon Energy, Cheasepeak Energy, Expand Energy, Love’s Travel Stop, Hobby Lobby, and Paycom
Unemployment Rate: Moderate
3–4.5%
Job Growth tracks a steady annual job addition
0.6% to 1.1%
Employees at Tinker Air Force Base, the metro’s largest single-site employer
24,000+
Homicide rate have dropped and top 10
lowest homicide rates the city has seen in the
past 35 years.
18%
Key Notes/Drivers: Energy/oil & gas, aerospace/defense, logistics, healthcare,
and government. Diversified with energy and aviation strengths.
Main Companies & Market Players
Local & Regional
We did not identify a single, dominant Oklahoma City-headquartered multifamily developer comparable to the local anchors profiled in other editions of this series in our sourcing for this edition.
National Platforms
Development activity has slowed sharply across the metro consistent with the broader construction pullback, with limited new project announcements identified in our sourcing for this edition.
Investors
Investment activity has slowed materially, with transaction velocity down 54% from 2024 to 2025 and pricing continuing to soften into 2026. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without concentrating risk in any single metro’s liquidity profile or price-discovery stage.
Submarket Intelligence
We did not identify granular, OKC-specific submarket-level performance data with the same resolution available for several other markets in this series and flag this as a data gap rather than present unsupported submarket distinctions.
Downtown Oklahoma City
Commands a premium over the broader metro average (approximately $1,350 for one-bedroom units), suggesting genuine urban-core demand distinct from the wider market’s more value-oriented positioning.
Broader Metro / Established Neighborhoods
Benefiting from reduced competitive pressure as new deliveries fall to a fraction of 2024 levels, supporting occupancy across established, well-maintained properties specifically.
Data Note
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
In a Nutshell
Oklahoma City in 2026 offers the lowest per-unit cost basis of any market in this series ($60,700, versus $119,000 or more elsewhere), paired with the region’s thinnest construction pipeline in over a decade. Vacancy remains tight by national standards even as a recent OKC-specific data point — negative Q4 2025 absorption and occupancy declines across most classes — warrants monitoring rather than dismissal. Tinker Air Force Base and the metro’s energy-sector headquarters provide durable, if sector concentrated, employment anchors. Oklahoma City functions as the most explicitly deep-value market in this series after Birmingham — appropriate for patient capital that can accept a smaller, less liquid market in exchange for a meaningfully lower entry basis.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.