
Phoenix multifamily presents a buy-earlier-in-the-cycle opportunity: stabilized properties impacted by the recent supply surge, and select value-add renovations in key employment hubs like Deer Valley, may be well positioned as the region’s steady population and income growth reassert themselves.
August 2026
Mid-2026 Outlook
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
Phoenix, Arizona serves as our inaugural edition and a foundational market in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, Phoenix exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
Longview Commercial focuses on building diversified institutional-quality multifamily portfolios for accredited and sophisticated investors. This report provides an independent assessment of the Phoenix multifamily sector as of mid-2026, emphasizing metrics that indicate market health, investment potential, and forward outlook.
Sources: Yardi Matrix, Marcus & Millichap, Northmarq, U.S. Census Bureau. Data as of Q1–Q2 2026.
Phoenix’s multifamily market continues to navigate an elevated supply cycle but shows clear signs of stabilization and early
recovery in 2026. Overall vacancy remains elevated compared to national averages and peer Sunbelt markets, though it improved modestly year-over-year.
Strong absorption, a sharp pullback in new construction, and a projected roughly 50% drop in completions for 2026 are positioning the market for reduced competitive pressure on existing assets.
The market is bifurcated: higher-end segments are gaining momentum as new supply eases, while value segments in certain areas face ongoing pressure. This creates selective opportunities for discerning, patient investors.
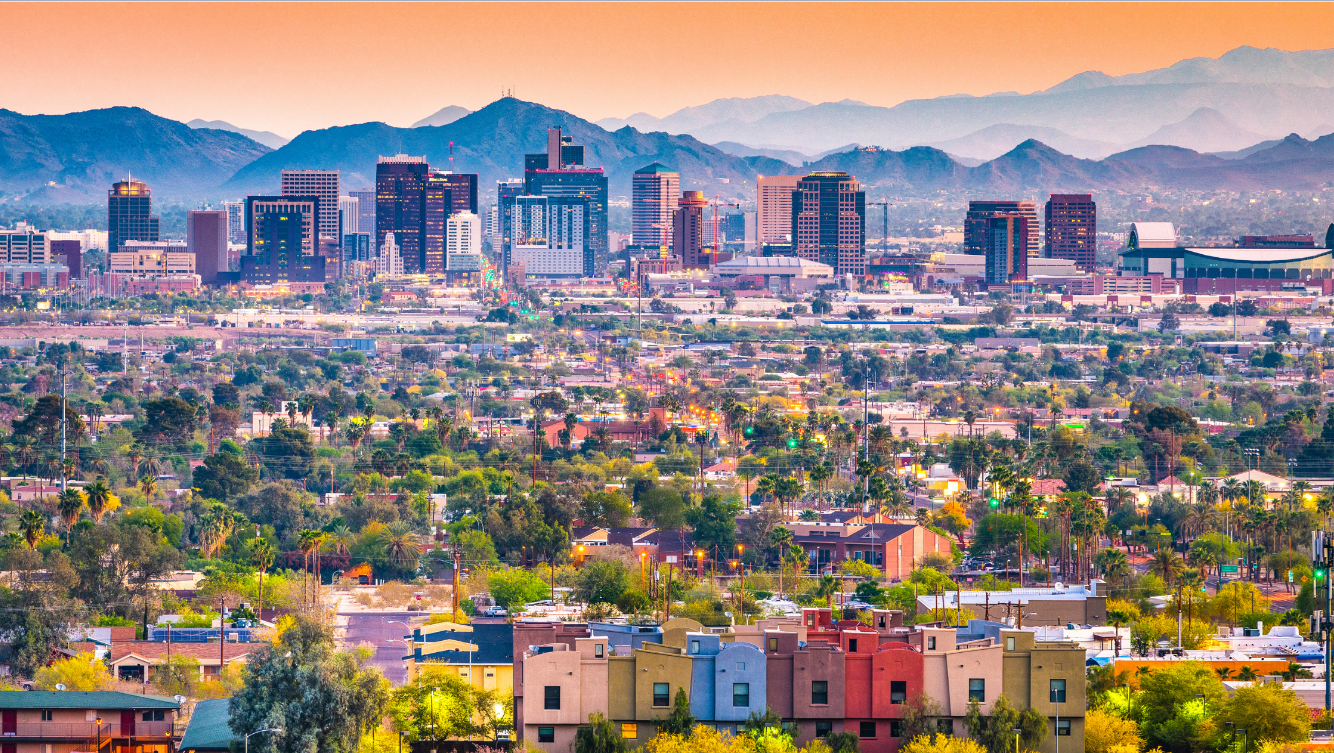
Metro Phoenix (Phoenix-Mesa-Chandler MSA) population stands at approximately 4.83–4.89 million (2025–2026 estimates), with annual growth around 1.1–1.5%. Long-term forecasts remain positive, supported by domestic migration, though rates are moderating from post pandemic peaks.
Job growth was slow in 2025 (approximately 0.3%) and is projected to accelerate modestly to roughly 0.7% in 2026. Unemployment hovers around 4.2%. The labor force benefits from in migration, with expansion in key sectors.
Diversified economy with strengths in healthcare, professional and white-collar services, manufacturing, logistics, technology/semiconductors, and hospitality/tourism. Steady job creation in healthcare and higher-wage sectors supports affluent renter segments.
Phoenix metro hosts several Fortune 500 companies, including Freeport-McMoRan, Avnet, Republic Services, PetSmart, and Insight Enterprises — roughly 5–10 major headquarters or significant corporate presences depending on ranking methodology. The region ranks solidly among U.S. metros for corporate headquarters.
Growing, relatively young and diverse population attracted by affordability relative to coastal markets, climate, and job opportunities. Strong renter demand from in-migration and household formation.
Positive trajectory. Homicides and overall violent crime declined in 2025 compared to prior years, with Phoenix PD data showing notable drops heading into 2026. Broader Arizona trends also reflect improvement in violent and property crime; a precise multiyear percentage decline was not available in our sourcing for this edition.
Overall, Phoenix retains strong structural appeal as a Sunbelt growth market, with demographic and economic fundamentals supporting long-term multifamily demand despite near-term cyclical pressures.
Avg. Sale Price / Unit (Q1)
~$222k
YoY Change
−12%
Phoenix exhibits higher vacancy and softer near-term rent performance than the national average, reflecting a more pronounced recent supply surge. However, the rapid pullback in construction and resilient absorption position it for relative catch-up in 2026 – 2027.
CURRENT (2026)
The market is adjusting to prior oversupply but benefiting from slowing deliveries and strong
absorption — thousands of units quarterly in recent reports.
Performance is split by corridors lead with vacancy compression and better Class A fundamentals, supported by affluent demographics and healthcare/white collar job growth.
West Valley and central areas lag, with greater pressure on Class B/C properties amid softer hiring in manufacturing, logistics, and hospitality. Low local inflation (under renter affordability.
5-YEAR OUTLOOK ( 2031)
Supply normalization accelerates recovery. With completions dropping sharply, vacancy should trend downward — particularly in stronger submarkets — enabling rent growth resumption, especially for Class A assets.
Resilient demographic demand and moderating economic headwinds support gradual tightening.
Investor focus likely shifts toward quality stabilized and value-add opportunities in outperforming corridors.
10-YEAR OUTLOOK
Long-term tailwinds remain intact. Continued, moderating, population and employment growth, migration appeal, and economic diversification position Phoenix as a sustained growth market.
Multifamily demand should strengthen as the market
rebalances, supporting attractive long-term performance for well-positioned assets.
—
Recent asking-rent trend, year-over- year
−3.0%
Q1absorption,upsignificantly year- over-year
4,496+ units
Overallvacancy (−10 bps year-over- year)
~11.8%
Average sale price per unit (recent Q1 data)
~$222,000
Rentescalationrangeas supply eases
~3.0–4.0%
Cap rates, generally
~6.0%
Metropopulation (2025 est.), strong long-term growth trajectory
~4.83–4.89M
Unemployment Rate
~4.1%
Job Growth: Strong; ~1.0% (recent YoY); strong industrial-led outlook
~1.9% projected
for 2026
Homicide & violent crime trend, 2025–2026(no precise multi-year % in current sourcing)
Improving
Key Notes/Drivers: Semiconductors/advanced manufacturing resurgence, tech, tourism/leisure, healthcare, and logistics. One of the stronger industrial growth stories in the Sunbelt.
Mark-Taylor Residential represents the strongest local development and ownership presence in the
Phoenix market.
Alliance Residential (Scottsdale/Phoenix presence), Weidner Investment Services, Greystar, and Western Wealth Capital, among others active in development and ownership.
A mix of institutional capital, private equity, and REITs, focusing on both stabilized yield and value-add strategies. Longview Commercial structures diversified portfolios to give investors access to institutional-quality multifamily without single asset concentration risk.
Submarket
Profile & Theme
Longview View
East Valley & North Phoenix– Scottsdale
Leading corridors with vacancy compression and stronger Class A fundamentals, supported by affluent demographics and healthcare/white collar job growth.
Favorable
Deer Valley
Referenced as a key employment hub for value-add and stabilized-asset opportunities amid past supply surges, per current market commentary.
Exploratory
West Valley & Central Areas
Greater pressure on Class B/C properties amid softer hiring in manufacturing, logistics, and hospitality; requires careful, asset-level selection.
Cautious
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
Phoenix multifamily in 2026 is in a transitional recovery phase following a significant supply surge. While vacancy remains elevated and rents pressured in the near term, the rapid easing of new construction, resilient absorption, and improving submarket dynamics signal building momentum. Long-term demographic and economic strengths position the market for gradual strengthening. Selective, high- quality exposure — particularly in stronger corridors and asset classes — offers compelling opportunities for patient institutional
investors.
Longview Commercial is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.
Website: www.longviewcommercial.com