
“San Antonio enters 2026 with the highest vacancy of any market in this series — and the sharpest construction pullback. An 80% collapse in new starts is precisely the kind of setup that turns a market from a cautionary tale into a contrarian entry point, if the timing is underwritten with real discipline.”
August 2026
Mid-2026 Outlook
Longview Commercial’s bi-annual, institutional-grade market intelligence publication — designed to give accredited investors, whether new to private real estate funds or experienced in direct asset ownership, a clear, unvarnished view of the markets we target for deployment.
Each edition focuses on a single metropolitan market, assessed across the dimensions that matter most: demographic momentum, employment health, supply/demand dynamics, capital flows, and submarket selectivity. Our goal is not simply to share data, but to translate that data into investment context relevant to a diversified multifamily portfolio.
San Antonio, Texas serves as our sixth edition and the most supply-challenged market in this series in the Longview portfolio strategy. As one of the nation’s most dynamic Sunbelt metros, San Antonio exemplifies both the opportunity and the nuance that sophisticated multifamily investing demands. The following pages present our mid-2026 assessment.
Longview Commercial specializes in constructing diversified institutional-quality multifamily portfolios for accredited and
sophisticated investors. This report delivers an independent, data-driven assessment of the San Antonio multifamily sector as of mid-2026, focusing on metrics that signal market health, investment viability, and long-term positioning.
Sources: Yardi Matrix, Marcus & Millichap, Northmarq, U.S. Census Bureau. Data as of Q1–Q2 2026.
San Antonio carries the highest or near-highest vacancy of any major U.S. metro depending on methodology: approximately 15.8% on an all-property basis (third-highest among the 50 largest U.S. metros per one national tracker) versus approximately 9.3% on a stabilized-property basis (Yardi Matrix, occupancy 90.7%). Rent growth has been negative for three consecutive years, with year- over-year figures ranging from approximately −0.6% to −3.3% across the sources we reviewed.
The offsetting signal is the size of the construction pullback: apartment starts fell approximately 80% in 2024 (1,874 units broke ground versus 9,526 in 2023), and 2026 completions are forecast to drop a further 21%. Demand remained resilient through the downturn — approximately 5,400 units were absorbed in 2025, helping contain further vacancy increases.
2026 is expected to mark the first annual vacancy decline since 2021, with vacancy projected to tighten by approximately 90 basis points.
The 80% collapse in 2024 construction starts is one of the sharpest supply pullbacks of any major Sunbelt metro in this series.
Employment growth of approximately 1.9% (as of mid-2026) ranks among the best in the nation, and San Antonio is projected to rank second in employment growth among major U.S. markets this year.
San Antonio ranks in the top five nationally for population growth among 20- to 34-year-olds over the past three years, supporting a durable long-term renter base.
Within the Longview portfolio, San Antonio is the most contrarian, earliest-stage opportunity of any market in this series — earlier in its cycle than Austin, with more elevated vacancy but also the most dramatic supply correction already underway.
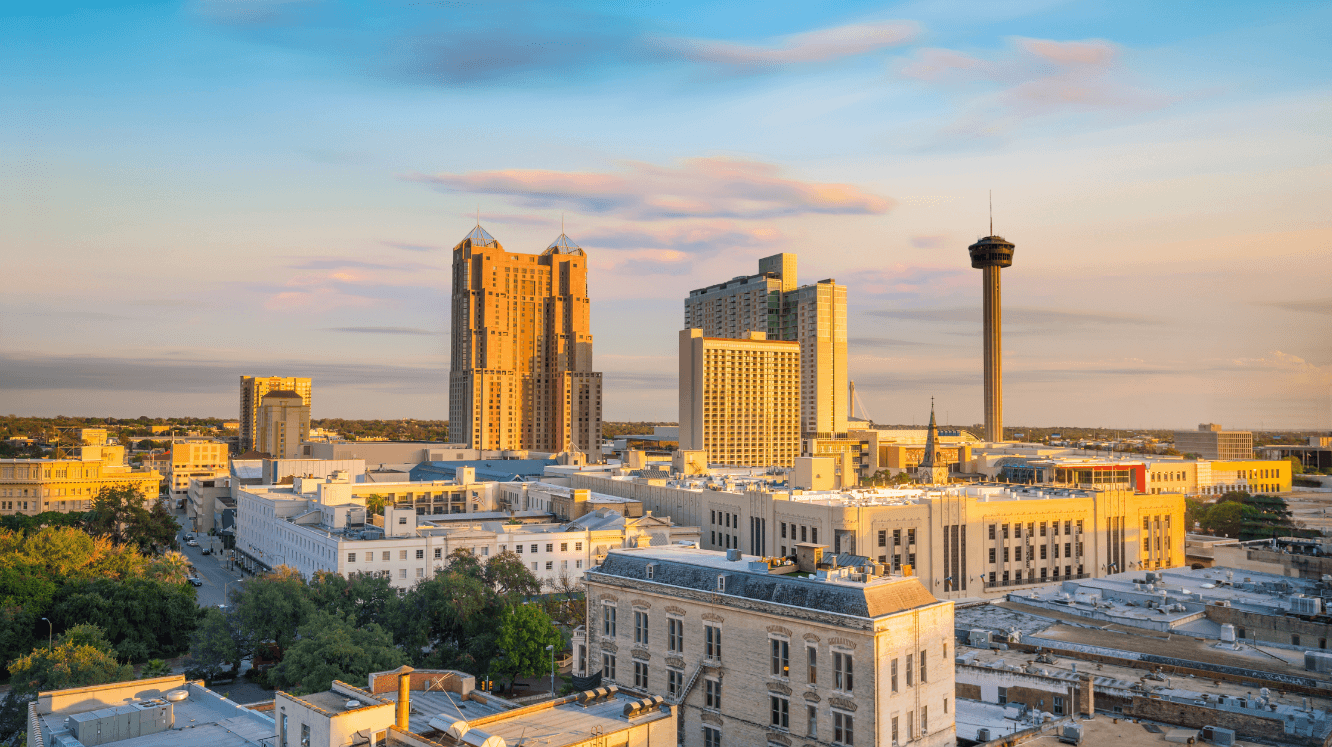
San Antonio added approximately 30,000 residents in 2024 and remains among the nation’s most moved-to cities, with population growth of approximately 0.9% in 2025 (Newmark). The metro ranks in the top five nationally for population growth among 20- to 34-year-olds over the past three years — a demographic squarely in the core multifamily renter cohort.
Employment growth measured approximately 1.9% as of mid-2026 (Yardi Matrix), among the strongest rates of any Longview-tracked market and well above the 0.8% national average. Unemployment stood at 3.9% in July 2026, below both the U.S. (4.2%) and Texas (4.0%) rates. Roughly three-quarters of the 23,100 net jobs added over the trailing period came from education/health services, trade/transportation/utilities, and government. San Antonio is projected to rank second in employment growth among all major U.S. markets in 2026.
Anchored by healthcare, government, and defense — San Antonio is home to Joint Base San Antonio (consolidating Lackland, Fort Sam Houston, and Randolph installations), one of the largest military concentrations of any U.S. metro, alongside a rapidly expanding South Texas Medical Center district. Tourism (the River Walk, the Pearl District) and a growing base of corporate employers round out the economy.
San Antonio’s major-company base is concentrated rather than broad: Valero Energy (Fortune 500, headquartered in San Antonio) and USAA (a large financial services and insurance company headquartered in the metro) anchor the corporate base, alongside H-E-B, one of the largest privately held companies in the U.S. This is a narrower Fortune 500 presence than Houston, Dallas-Fort Worth, or Atlanta, balanced by San Antonio’s unusually deep military and healthcare employment base.
San Antonio is consistently ranked the most affordable major Texas metro: average rents of roughly $1,180–$1,264 run below every other Texas market in this series, and for-sale housing costs run at roughly 40–60% of Austin’s and Dallas’s levels. This affordability is a genuine double-edged consideration for investors — it drives consistent renter demand but also compresses revenue potential and development economics relative to higher-rent metros.
A sustained, multi-year improvement. San Antonio Police reported overall crime down 13% in 2025, with homicides falling approximately 17–20% (from 119 to 99 cases per SAPD’s own report) and property crime down 18.1%. The city’s hot-spot policing strategy, in place since 2023, has been independently evaluated by UT San Antonio and associated with a 22% violent-crime reduction in targeted areas. One exception worth noting: reported rapes increased year-over-year in the most recent reporting period, a genuine counter-trend within an otherwise positive picture.
Overall, San Antonio combines the strongest employment growth rate and one of the most consistent crime improvement trends of any Longview-tracked market, set against the most significant supply overhang and narrowest large-corporate base in this series.
2023 Construction Starts
9,526 units
YTD Through March 2026
~$672M
San Antonio is the clearest supply-correction story of any market Longview tracks. Where Austin’s pullback has been a slowing growth rate, San Antonio’s has been a near-collapse in new construction starts — the kind of dislocation that, if demand holds as it did through 2025, tends to set up a sharper-than-average recovery.
CURRENT (2026)
Vacancy sits at the high end of any market in this series on an all-property basis, though the stabilized-property figure is more moderate. Rent growth has been negative for three consecutive years.
Performance is bifurcated: the Pearl District and Southtown (vacancy below 10%, rent declines limited to 1–2%) have held up far better than oversupplied corridors along I-10 West and Highway 151, even as the broader Far Northwest submarket has posted strong recent absorption.
Class A assets delivered at the 2024 supply peak are approaching stabilization and are market for sale in 2026.
5-YEAR OUTLOOK ( 2031)
With construction starts down 80% and 2026 completions forecast to fall a further 21%, 2026 is expected to mark the first annual vacancy decline since 2021 — a meaningful inflection point if it holds.
As the pipeline thins further, the gap between the strongest urban-infill submarkets and the most supply- heavy suburban corridors should narrow.
Increased Class A transaction volume in 2026 should provide clearer pricing signals for the broader market.
10-YEAR OUTLOOK
San Antonio’s affordability, military employment base, and top-five ranking for young-adult population growth support a durable long-term demand floor beneath the current supply correction.
Properties near San Antonio’s military installations show a distinct, durable occupancy advantage — a differentiated submarket dynamic specific to this metro.
Core and core-plus capital seeking long-term exposure to one of Texas’s most affordable markets should find increasing opportunity as supply rebalances.
Construction starts, 2024 vs. 2023 (1,874vs. 9,526 units) — a data point for this market
-80%
2026completions forecast, year-over- year
−21%
Stabilizedoccupancy (Yardi Matrix); all- propertyvacancy runs materially higher
90.7%
Average rent—the lowest among major Texas metros in this series
~$1,180–1,264
2025 absorption, helping contain further vacancy increases
~5,400 units
Employment growth, among the strongest of any Longview-tracked market
1.9%
Employment growth, among the strongest of any Longview-tracked market
1.9%
Job Growth: Modest, occasional flat or slight contraction in specific months but positive long-term
~0.4% in some recent periods
2025 crime and homicide decline (SAPD), continuing a multi-year downward trend
−13% to −20%
Key Notes/Drivers:
Military/government, healthcare, tourism/leisure, finance, and manufacturing. Steady but more measured growth compared to Austin or Dallas.
The NRP Group (Cleveland-based, but with San Antonio as its single largest metro nationally) has developed more than 14,000 apartment units across 64 communities in San Antonio since 2003 — a scale of local concentration unmatched by any developer in the other markets in this series.
NRP Group ranks #2 nationally on the National Multifamily Housing Council’s 2026 Top Builders list, with active San Antonio projects including a partnership with the Brooks Development Authority near Toyota’s local manufacturing operations and a new $44 million project on the city’s far West Side.
Much of San Antonio’s recent development activity has centered on mixed-income and affordable housing partnerships alongside market-rate product, reflecting both public-private collaboration and the metro’s structural affordability positioning. Longview Commercial structures diversified portfolios to give investors access to institutional- quality multifamily without concentrating risk in any single metro’s cycle stage — San Antonio’s earlier-stage correction pairs differently in a portfolio than Houston’s more advanced recovery.
Submarket
Profile & Theme
Longview View
Pearl District & Southtown
San Antonio’s strongest submarkets by a clear margin: vacancy below 10% and rent declines limited to just 1–2%, anchored by the Pearl’s successful urban revitalization.
Favorable
Military-Adjacent Communities (Joint Base San Antonio)
Properties actively serving the military community with deployment support and flexible lease terms achieve measurably higher occupancy and retention than comparable non-military-focused properties.
Favorable
Far Northwest & Kerrville
Cited by Northmarq among the market’s top-performing recent submarkets, even as portions of the broader northwest corridor carry some of the metro’s heaviest supply.
Selective
I-10 West & Highway 151 Corridors
The most concentrated oversupply in the metro, where rapid population growth attracted development activity that has, to date, exceeded near- term demand.
Cautious
Submarket views reflect qualitative positioning drawn from broker and proprietary market research as of mid-2026. Granular submarket-level rent and occupancy data were not available at point-estimate resolution for this edition and are flagged rather than estimated.
San Antonio in 2026 is the most supply-challenged market Longview currently tracks — and the site of the sharpest construction correction in this series, with starts down approximately 80% from 2023 to 2024. Vacancy remains elevated and rent growth has been negative for three years, but demand has stayed resilient, employment growth ranks among the nation’s best, and 2026 is expected to mark the first annual vacancy decline since 2021. This is the most contrarian, earliest-stage opportunity in the
Longview Texas portfolio
— one where patient, disciplined capital stands to benefit most if the current inflection holds.
Longview Commercial
is positioned to help accredited investors access high-quality, professionally managed multifamily exposure in this evolving market. All projections involve uncertainty; investors should conduct independent due diligence and consult offering documents.
To learn more about Longview Commercial fund offerings or to request placement on the investor distribution list for the Market Intelligence series:
Website: www.longviewcommercial.com